Column: How Music Tech is Making it Easier — and Harder Than Ever — for Artists

Larry Miller

Larry Miller is a professor at NYU where he directs the undergraduate and graduate Music Business programs. He produces and hosts the Musonomics podcast.

Column: How Music Tech is Making it Easier — and Harder Than Ever — for Artists

For many musicians, the democratization of music production and distribution carried the promise of reaching multitudes of eager fans at the touch of an upload button.

Yet with over 40,000 new tracks being uploaded each day, creating a virtually infinite selection of music available on most streaming platforms, breaking through as an artist has in some ways become more difficult than ever, especially on the global stage.


It is certainly possible today for artists to create and self-distribute their music, gain a following and begin building a career. But there's a big difference between having access to the tools of music creation, distribution, and building a sustainable career and the potential to become a global superstar. And that's where modern record labels are best positioned to help.

So What Does a Music Label Do These Days?
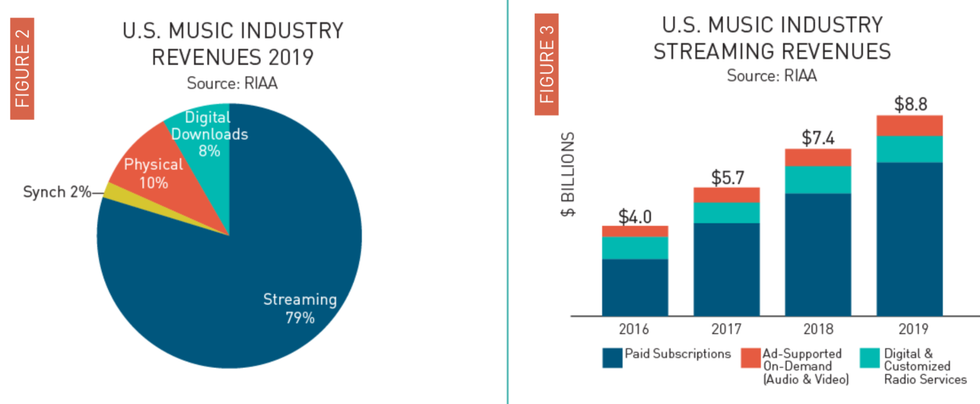
Revenues from recorded music in the United States grew 13% in 2019 to $11.1 billion at estimated retail value.

Image from The Recording Industry Association of America's report on year end revenues for 2019.

Fact is, what record labels do has not changed much since the industry's digital transformation. Now, as ever, labels discover and develop artists, connect them with creative collaborators to make great records, promote and position them in the media and wherever fans go to get music and reward successful outcomes. Over the last decade or so, the digital transition has fundamentally changed how and when virtually every functional area of a record label is done.

One difference that touches every facet of a label's operation is the massive amounts of real-time discovery and consumption data. Label teams analyze thousands of global inputs: Facebook fans, Twitter followers, YouTube views, Instagram activity, Shazam queries and Wikipedia look-ups. That's on top of analyzing the daily tsunami of music service plays around the world. The end goal: to develop an agile, highly customized response plan for every track of an artist's release.

Corollary to all this data is how today's music fans discover and consume music. Many fans now listen to music via premium subscription services that give them access to tens of millions of tracks for less than the price of one CD per month, or in a "feels free" option of ad-supported delivery. Fans also access music by watching label-created visual content on a myriad of screens, large and small, over video channels and via social media. At the same time they may still buy CDs or vinyl records and listen to the radio. To properly synthesize and optimize all these inputs and extract actionable insights requires hands-on experience that is both broad and deep, relationships, investment and instant access to a global marketing and distribution network; that is, it requires boots on the ground. Lots of them.

Revenues from recorded music in the United States grew 13% in 2019 to $11.1 billion at estimated retail value, the fourth year in a row of double digit growth reflecting continued increases — primarily from paid subscription streaming services, which reached more than 60 million subscriptions in the United States and accounted for 80% of recorded music revenue.

To put these numbers in a global perspective, as recently as 2018 and with streaming growth surging in developed markets, the worldwide recorded music business generated not quite half the peak revenues achieved in 1999 on an inflation-adjusted basis. CD sales crashed after 1999 with the launch of Napster and other illegal peer-to-peer file trading services, all of which were eventually litigated out of existence. The growth of iTunes downloads beginning in 2003 mitigated the decline of CD sales; Spotify didn't enter the U.S. market until 2011, the same year global revenues returned to growth after over a decade of painful decline. Midia Research pegged the 2019 global music industry at $76.2 billion including recorded music, publishing, live music, merchandising and sponsorships.

And just as the mode of consumer listening has shifted from mostly physical products and permanent downloads to on-demand streams, every aspect of label operations has reoriented toward a streaming-first consumption model and an always-on consumer mindset. The business of minting hits is no longer narrowly based on the 20th century model of maximizing short-term campaign outcomes for scarce broadcast radio slots or displays in retail stores. Every label function is now organized around fighting for a share of the attention economy, where consumers have unlimited access and choice, but not unlimited time.

Welcome to the Age of the Artist
The Age of the Artist

Photo by @plqml // felipe pelaquim on Unsplash

Today, an artist's decision to partner with a label is a choice, not a requirement. The expanding galaxy of startups designed to help the DIY artist record, distribute, and market digital music has given artists more options to stay independent longer, and enables some artists to make a sustainable living while building a fan base. Every musician starts out as an independent, DIY project. When they attract the attention of a record label, whether indie or major, they may be in a very different negotiating position than a decade or so ago. In this way, the point at which labels interact with artists has largely shifted to a point that's further along an artist's development.

Although labels continued to invest in developing and breaking new artists during the industry's downturn following an explosion of file sharing led to the collapse of the CD earlier this century, the improvement in industry revenue, driven by the growth of subscriptions to streaming services, is being re-invested in A&R.

Two years ago, 12% more artists signed to major label rosters for the first time as compared with the end of 2014. I'll be doing research to update this data later this year, but all signs point to further growth in artist signings. At the same time, independent artists are the fastest-growing segment in the music economy, so much so that industry analyst Mark Mulligan has dubbed the 2020s The Age of the Artist, a fundamental departure from previous decades/eras defined by a mode of distribution or packaged media format.

Major labels understand it is in their interest to maintain a front-row seat to the edge of innovation through various approaches. For example, Warner Music's WMG Boost invests directly in early stage companies; Universal's Accelerator Engagement Network invests through top accelerators located in innovation hubs around the world. But as the world's largest music-based entertainment companies and guardians of a century of the world's most popular music, their attention is focused elsewhere.

Where Is the Investment in New Music Technology Going?
Where Is the Investment in New Music Technology Going?

Photo by James Owen on Unsplash

So where exactly is the innovation occurring? The current cohort of international startup competitions like MidemLab and those receiving support from top accelerators like L.A.'s Techstars Music or Abbey Road Red fit into an emerging post-pandemic investment pattern.

  1. Creator tools. There is a mind-numbing array of unbundled offerings for artists to support collaboration, production and mastering, funding and financial management, distribution, marketing and promotion. A generation of data insight and analytics startups were acquired by the majors along with Spotify, Apple Music and Pandora. HiFi, a new entrant in financial management and transparency, was launched with $53 million in backing 'to financially empower the creative class.'
  2. Live streaming and virtual events. The live concert business came to a screeching halt to mid-March. Touring represents 70 – 80% of revenue for many artists. Virtually no one expects a meaningful restart of this segment until 2021. And although live streaming and virtual events are not a substitute for the live concert experience, this trend is likely to stay with us even after the pandemic recedes.
  3. The New Merch – In China, Tencent Music has done a spectacular job proving music fans will pay for virtual goods, gifts and currencies – at scale. This is especially noteworthy in a market not known for generating revenue directly from the sale of recorded music. Now, the West is paying attention. Opportunities abound in limited edition merchandise, premium chat services, virtual merchandise and much more.

Over the last two decades, the music industry has faced extreme disruption as digital services were born and entered the mainstream. Independent and unsigned artists have a myriad of options to self-release their music. While some musicians have found sustainable success without a label's backing, there are certain things that only a label can do, particularly for artists with global ambition. Opportunities for innovation and value creation are distributed across the music industry value chain, especially in the areas of creator tools, live streaming and monetizing fandom. It's no secret that many of the most exciting startups envisioning the way music will be created and experienced are in L.A. today.

Larry Miller is a professor at NYU where he directs the undergraduate and graduate Music Business programs. He produces and hosts the Musonomics podcast.

Northwood’s Nine-Month Rise to $2B
Northwood

🔦 Spotlight

Happy Friday, Los Angeles.

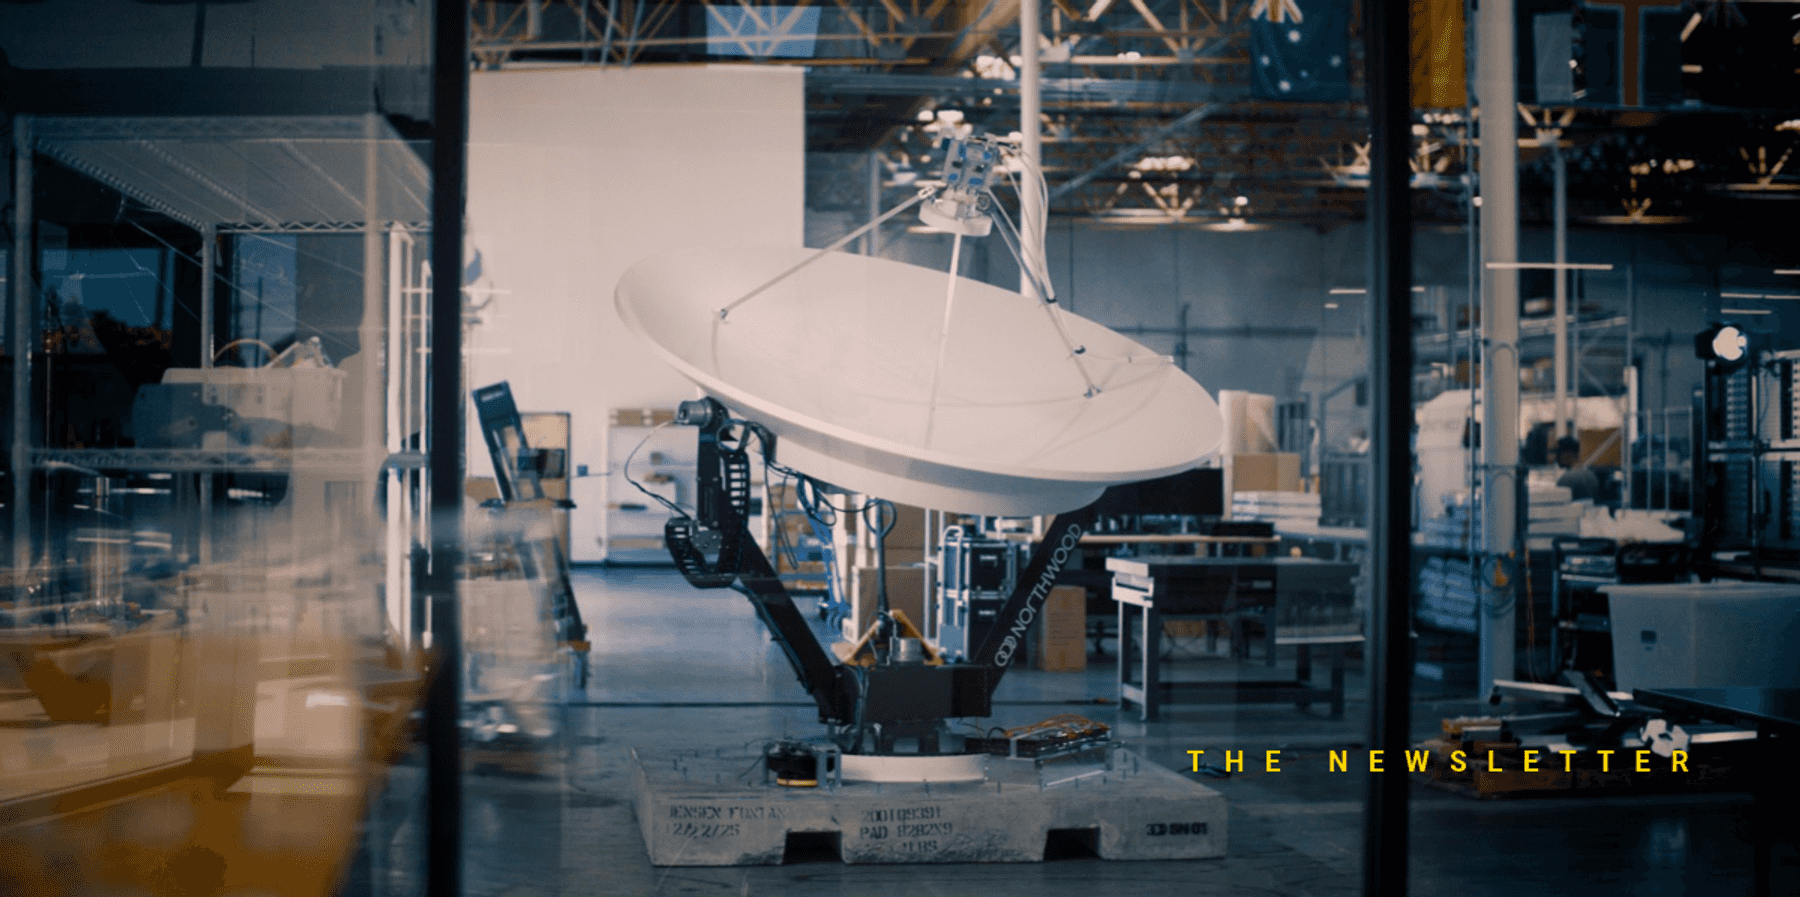
Nine months ago, Northwood Space was operating from a 35,000-square-foot facility in Torrance. Today, it occupies a factory more than five times the size, has deployed six ground sites across two continents and is reportedly worth $2B.

Aerospace companies are not generally known for moving this quickly.

When dot.LA last covered Northwood, the company had just raised a $100M Series B and secured a nearly $50M contract with the U.S. Space Force. The deal established Northwood as one of the more closely watched companies working on the essential infrastructure that keeps satellites connected to Earth.

Less than a year later, Northwood is operating at a considerably different scale.

The company announced this week that it raised a $375M Series C co-led by Andreessen Horowitz and DFJ Growth, with additional investment from Washington Harbour Partners, Alpine Space Ventures, StepStone, In-Q-Tel and others. The round values Northwood at a reported $2B. A separate credit facility from HSBC Innovation Banking will provide additional support for working capital and network expansion.

The financing is notable. What Northwood accomplished between rounds is the more interesting part.

Since January, the company has deployed six ground sites across two continents, demonstrated communication with a government satellite in geosynchronous orbit and introduced a high-throughput antenna system for moving larger volumes of data. It also opened a 185,000-square-foot headquarters and factory in Torrance, expanding its manufacturing footprint more than fivefold.

Northwood now employs more than 140 people and plans to add 400 jobs across Torrance and Washington, D.C., over the next three years.

The company builds the infrastructure that allows satellites to exchange commands and data with operators on Earth. Rather than requiring every satellite company to develop its own ground stations, Northwood is creating a shared network that commercial operators and government agencies can access as needed.

Think cloud infrastructure, except the servers are antennas and adding capacity requires considerably more than clicking a button.

That distinction matters. Software companies can often scale by purchasing additional computing power. Northwood must manufacture physical systems, establish sites around the world and reliably serve customers operating across multiple orbits.

Its new Torrance factory is central to that plan. The facility is designed to produce hundreds of antennas each year, giving Northwood the manufacturing capacity to expand its network faster than traditional ground infrastructure can typically be built.

Demand is moving just as quickly. The number of active satellites worldwide grew from roughly 3,000 in 2020 to more than 14,000 by the end of 2025. Every one of them eventually needs to send information somewhere, and existing ground networks were not designed for the volume of missions now entering orbit.

Northwood’s previous funding helped prove it could build the technology and win serious customers. This round is about turning that early progress into global infrastructure.

The question is no longer whether Northwood can build a modern ground network. It is whether the company can make Torrance-built hardware the default connection layer for a rapidly expanding space economy.

With another $375M behind it, that test begins now.

More from this week’s LA startup and venture scene below.

🤝 Venture Deals

    LA Companies

    • Guava, a Los Angeles-based developer platform for building AI voice agents, raised a $12.5M seed round led by Acrew Capital, with participation from Flourish Ventures, WillowTree Ventures, Clocktower Ventures and existing investor Commerce Ventures. The company will use the funding to further develop its voice AI models and products while building a go-to-market team focused on enterprises and business process outsourcing providers. - learn more

    LA Venture Funds
    • Blue Bear Capital participated in Ocient’s $100M Series C alongside Greycroft, In-Q-Tel, Buoyant Ventures and other existing investors, while BOKA Capital and OCA Ventures co-led the round. The data analytics and AI infrastructure company will use the funding to expand OcientAIQ, its platform for delivering fast, reliable answers from petabyte-scale datasets, and bring its technology to more customers globally. - learn more
    • Mystic Ventures participated in Siggy’s $6M pre-seed round, which was led by Village Global and also included PsyMed Ventures, Coalition Operators and several angel investors. Founded by veterans of Nurx and Journey Clinical, Siggy combines AI, wearable data and licensed clinicians to monitor patients between mental health appointments, with the funding supporting product development, regulatory work and hiring across its clinical and engineering teams. - learn more
    • Grid Capital and Thin Line Capital participated in Strive Robotics’ more than $3M pre-seed round alongside Tenon Ventures, with Hi Ventures leading the financing. The Cambridge-based startup develops adaptable robots that can learn complete manufacturing workflows and operate existing factory equipment, with the funding supporting product development, hiring and early customer deployments. - learn more
    • Sum Ventures participated in Circularity Fuels’ $7M seed round alongside Automotive Ventures, with DCVC and Trucks Venture Capital co-leading the financing. The company converts dairy biogas into sustainable aviation fuel and will use the capital to build a demonstration plant, design its first commercial facility and begin licensing its reactor technology to outside partners. - learn more
    • Griffin Gaming Partners participated in EloElo Group’s $80M Series C alongside MIT Investment Co., Play Ventures, Kalaari Capital and WaterBridge Ventures, while Hornbill Capital and NBCUniversal co-led the round. The Bengaluru-based entertainment company will use the funding to produce more original microdramas across multiple languages, expand its Story TV platform internationally and continue developing Dolphin AI, its AI-powered creative suite. - learn more
    • Mucker Capital participated in Lazarus AI’s $43M funding round alongside QBE, State Farm Ventures, Wave Function Ventures, Techstars and several other investors. The Boston-based company develops AI systems for enterprises and government agencies that retain control over their data, models and deployment, with the new capital supporting research and development, strategic partnerships and new product launches. - learn more
    • Alexandria Venture Investments continued its support of Thryv Therapeutics by participating in the company’s $30M Series B, which was led by InClin and included several other existing investors. The clinical-stage biotech will use the funding to launch a Phase 2a study of THRV-1268 in patients with heart failure and evaluate the drug’s safety and potential effects on cardiac function and arrhythmia risk. - learn more
    • Supply Change Capital led Kodiact’s $2.5M pre-seed round, with participation from Green Circle Foodtech Ventures and Velocity Catalyst. Kodiact helps manufacturers anticipate raw-material price swings and simulate sourcing decisions, and will use the funding to expand its market data and AI capabilities, grow enterprise deployments and enter additional industries including cosmetics, packaging and chemicals. - learn more

      Download the dot.LA App

      Anduril Built Fighter Jets. Now It’s Making a Laptop.
      Anduril

      🔦 Spotlight

      Happy Friday, Los Angeles.

      Anduril has built autonomous drones, underwater vehicles and fighter aircraft. Its newest product is considerably more familiar.

      A laptop.

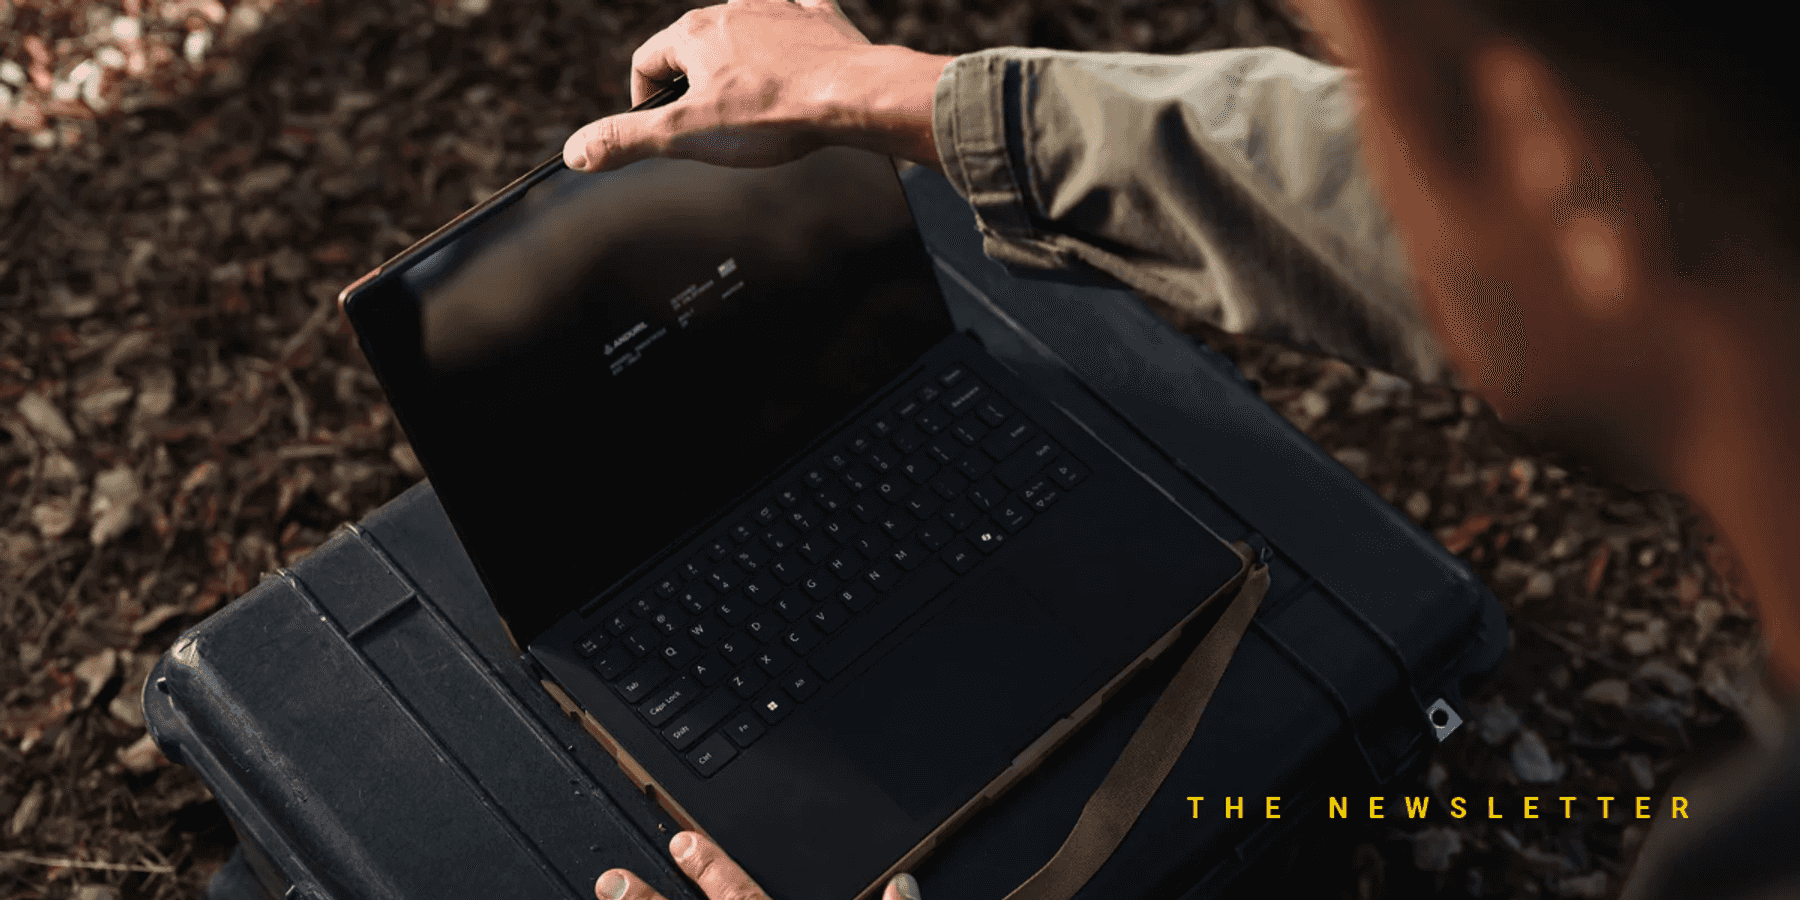
      The Costa Mesa-based defense technology company announced this week that it is partnering with San Diego-based Qualcomm Technologies to launch BlueChip, a new line of computers designed in California and manufactured in the United States.

      The first product will be a rugged laptop powered by Qualcomm’s Snapdragon X Series platform and built for customers in government, defense, public safety and other critical industries. Anduril has already produced working prototypes and plans to begin accepting orders in 2027.

      At first glance, a laptop may seem like a modest addition to a company known for developing autonomous military systems. But BlueChip is less about entering the crowded consumer-electronics market and more about rebuilding the industrial foundation behind the machines Americans use every day.

      The United States remains a leader in designing advanced technology, but much of the physical production required to turn those designs into finished computers has moved overseas. That includes not only semiconductor manufacturing, but also circuit boards, displays, batteries, enclosures and the network of specialized suppliers that connects them.

      For most consumers, that dependency is largely invisible. For the government and military, it represents a potential vulnerability.

      BlueChip is Anduril’s attempt to close that gap.

      Components sourced from the United States and allied countries already account for more than 90% of the prototype laptop’s procurement cost. Circuit-board assembly is planned for Anduril’s Arsenal-1 facility in Ohio, while the company develops domestic production capabilities for enclosures, batteries and other hardware.

      The goal is to gradually replace remaining foreign dependencies and create an end-to-end American computer supply chain that can support additional products beyond the first laptop.

      That process requires more than moving an existing design into an American factory. Anduril is redesigning the computer around what domestic manufacturers can realistically produce at scale. The work includes selecting machinable American metals, adapting power systems to available battery technology and developing a bonding process for domestically made display glass.

      In other words, Anduril is not simply assembling a laptop in America. It is working backward through the supply chain to make American assembly possible.

      Qualcomm will supply the computing foundation. Its Snapdragon X platform will handle processing, graphics and on-device artificial intelligence, giving BlueChip users the ability to run certain AI models locally rather than sending sensitive information to the cloud.

      That is particularly valuable for government and defense customers operating in secure environments, but it also reflects a broader shift in computing. As AI becomes embedded in everyday workflows, the location where information is processed may become nearly as important as the model doing the processing.

      The partnership also reinforces Southern California’s growing role in the effort to rebuild American advanced manufacturing.

      Anduril remains headquartered in Orange County, but its regional footprint is expanding. The company is investing $1B in a new campus spanning Long Beach and Lakewood that is expected to support approximately 5,500 jobs and include engineering, laboratory and prototype-manufacturing space.

      Qualcomm, meanwhile, has spent decades building San Diego into a center for wireless technology and semiconductor design.

      BlueChip brings those two Southern California strengths together: Anduril’s ability to move quickly from engineering concept to physical product and Qualcomm’s expertise in efficient, high-performance computing.

      The first BlueChip laptop is not intended to compete for space in every backpack or coffee shop. Its early customers will likely be institutions that care deeply about security, reliability and control over their technology supply chains.

      But the larger ambition reaches far beyond a single device.

      If BlueChip succeeds, Anduril and Qualcomm will have created more than an American-made computer. They will have helped restore the suppliers, production knowledge and technical workforce required to build the next one.

      For a company accustomed to tackling difficult national-security problems, the laptop may be one of Anduril’s most practical ideas yet.

      Sometimes rebuilding an industry begins with reopening the machine.

      More from this week’s LA startup and venture scene below.

      🤝 Venture Deals

        LA Companies

        • StimCardio raised an oversubscribed $30M Series A led by Metis MedTech, with participation from Catalyst Health Ventures and other investors. The Los Angeles medical device company will use the funding to advance a pivotal study of Rhyvive, its investigational wrist-worn therapy designed to reduce recurring atrial fibrillation after catheter ablation, and prepare for an FDA submission. - learn more
        • Gardena-based Neuron Industries raised an oversubscribed $10M seed round co-led by FCVC and Obvious Ventures, with participation from Y Combinator, Thin Line Capital, Zee Prime Capital and Founder Factor. The company will use the funding to develop and launch its AI-powered industrial control platform, expand its product line and establish domestic production as it works to help engineers automate new factories and machinery more quickly. - learn more
        • Offe Market raised a $3M seed round led by Slauson & Co., bringing the off-price retail marketplace’s total funding to $4.3M. The company will use the capital to expand its commerce platform with AI-powered pricing and inventory tools, personalized recommendations and live shopping features designed to help brands sell excess merchandise without sacrificing control over presentation or pricing. - learn more
        • Loamy raised a $6M seed round led by Zeal Capital Partners, with participation from LA investors Slauson & Co., Supply Change Capital and Amplify.LA, bringing its total funding to $10M. The company will use the capital to expand its engineering and sales teams, advance its AI platform and enter additional food categories as it helps growers, packers and distributors reduce waste and prevent rejected shipments. - learn more

        LA Venture Funds
        • MaC Venture Capital co-led Rendezvous Robotics’ oversubscribed $20M seed round alongside Toyota Ventures, marking the space startup’s first priced financing. The company will use the funding to develop its next-generation modular spacecraft, expand its team and prepare for flight demonstrations of technology that allows spacecraft components to assemble and reconfigure autonomously in orbit. - learn more
        • BOLD Capital Partners participated in General Compute’s $100M Series A, which was co-led by Blackbird and Abstract. The company will use the funding to scale its AI inference cloud, which deploys specialized chips from companies including Cerebras, SambaNova and Positron AI to help customers run AI workloads faster without managing the underlying infrastructure. - learn more
        • Mantis Venture Capital participated in Vera Health’s $28.5M Series A, which was led by Threshold Ventures and brought the clinical AI company’s total funding to $32M. Vera will use the capital to strengthen its medical-evidence infrastructure, enter new healthcare markets and expand partnerships with medical societies, publishers and health systems. - learn more

        LA Exits

        • Breastfeeding platform Swehl was acquired by Willow Innovations alongside infant-feeding technology company Momtech, with financial terms undisclosed. Swehl’s educational resources and community programs will anchor Willow World, a new platform designed to expand Willow’s business beyond wearable breast pumps and support mothers across more of the postpartum journey. - learn more
        • SmartLess Mobile was acquired by Noble Mobile and will transition to the Noble brand as the companies combine their efforts to offer simpler, more affordable wireless service. Existing customers will retain their plans, prices, phone numbers and T-Mobile 5G coverage, while gaining the ability to use their data in Mexico and Canada at no additional cost; financial terms were not disclosed. - learn more

          Download the dot.LA App

          Your Bank Wants to Cancel Your Subscriptions

          🔦 Spotlight

          Hello, LA.

          Somewhere between the streaming service you still use and the free trial you forgot to cancel, recurring payments have become a surprisingly complicated part of modern financial life.

          Los Angeles-based ScribeUp believes your bank should help manage them.

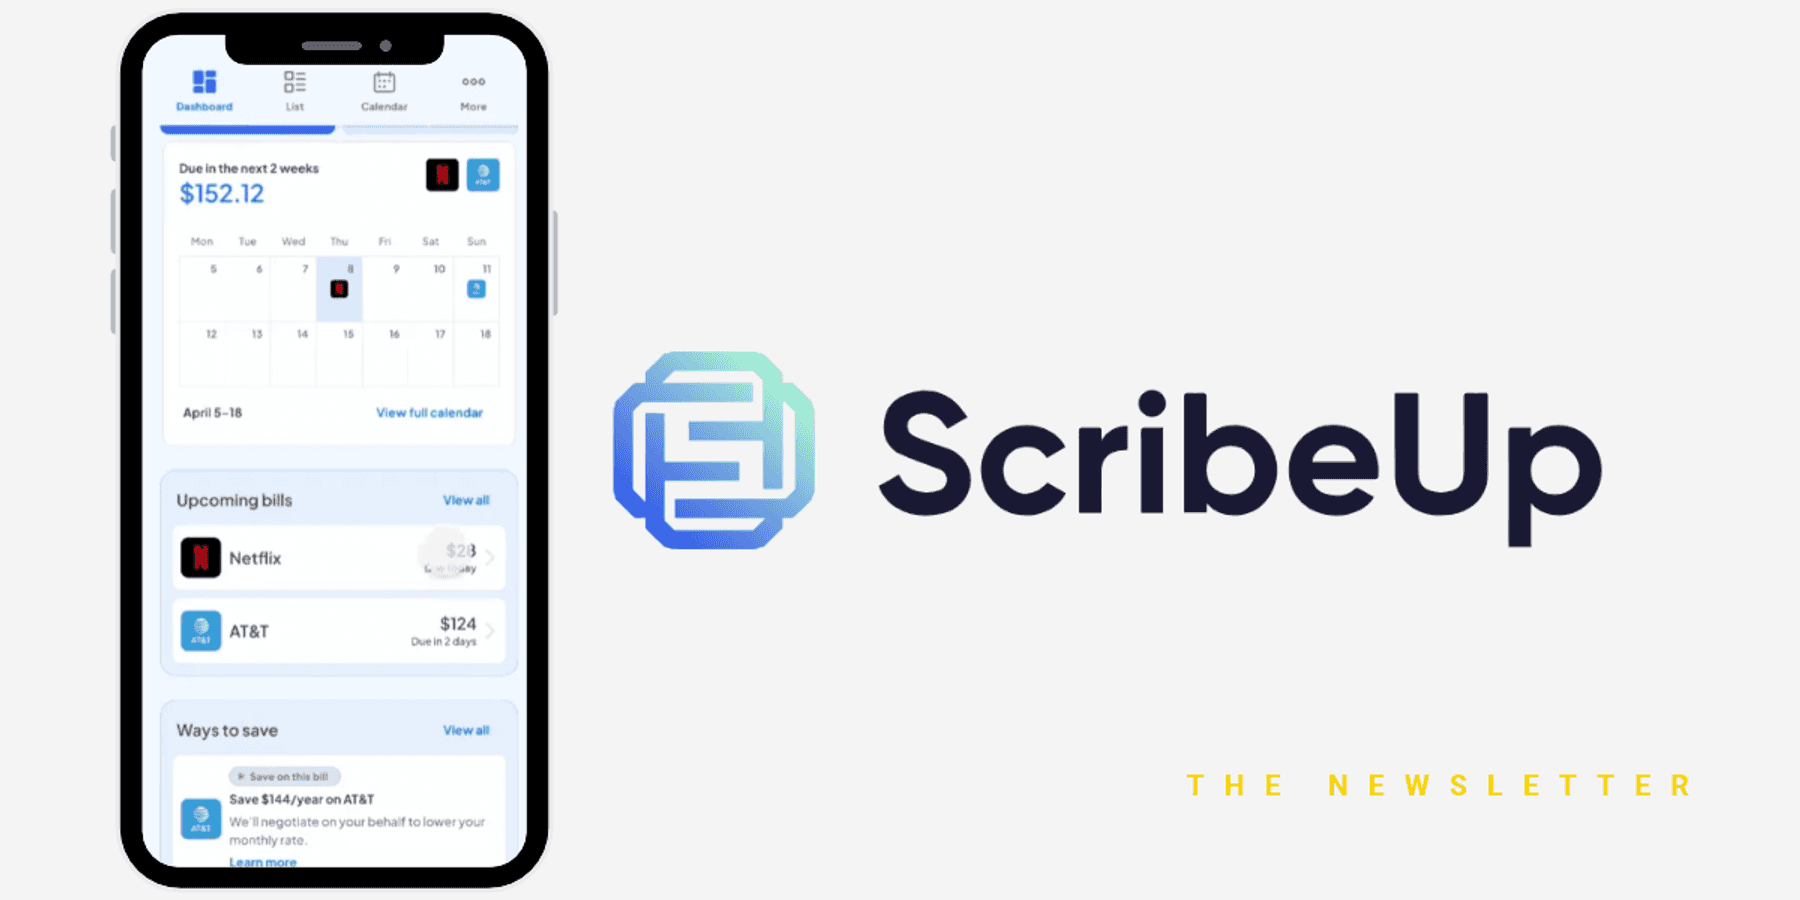
          The fintech company raised a $13M Series A led by Curql, with participation from Mucker Capital and Service Ventures. The financing includes $10M in equity and a $3M venture debt facility, bringing ScribeUp new capital to expand its team, accelerate sales and further develop its AI-powered bill-management technology.

          The product is designed to live directly within the apps of banks, credit unions, fintechs and neobanks. Instead of simply showing customers that a recurring charge occurred, ScribeUp gives them tools to do something about it.

          That could mean canceling a forgotten subscription, changing a payment method, accessing an advance or exploring refinancing options for an outside loan, all without leaving the financial institution’s app.

          It sounds like a useful feature. It is also part of a much larger contest over who gets to manage the consumer’s financial life.

          For years, banks have held customers’ money while third-party apps have increasingly helped them understand and manage it. Budgeting platforms organize spending. Subscription services identify recurring charges. Fintech apps recommend ways to save, borrow or invest.

          Now AI assistants are beginning to combine those functions into a single interface capable of not only analyzing financial information, but acting on it.

          That creates a risk for traditional financial institutions. If consumers begin turning to an outside app whenever they need to cancel a service, manage a bill or make a financial decision, their bank could become little more than the infrastructure beneath someone else’s customer experience.

          ScribeUp offers banks a way to compete without building that technology themselves.

          Its platform combines recurring-payment information with the financial context a bank already has, including balances, cash flow and payment timing. That allows a financial institution to do more than flag an upcoming charge. It can potentially recommend and execute an action based on the customer’s broader financial position.

          ScribeUp says its technology is already used by more than 60 banks, credit unions, fintechs and neobanks. It can be added through an API, software development kit or embedded interface, allowing institutions to introduce bill-management features without creating the underlying infrastructure from scratch.

          The new funding will support more advanced AI capabilities that can take action across different billers. That distinction matters. The first generation of personal finance software helped people see where their money was going. The next generation wants permission to do something about it.

          For banks, the opportunity is straightforward: become more useful before another app takes their place.

          For consumers, the appeal may be even simpler. Most people do not want another financial dashboard. They want the unwanted charge to stop.

          The next battle in banking may not be over who holds your money.

          It may be over who gets to press cancel.

          More from this week’s LA startup and venture scene below.

          🤝 Venture Deals

            LA Companies

            • International Dance League raised a $15M Series A led by Elysian Park Ventures, with participation from Sony, KB Partners, APEX, Yamaha Music Innovations Fund and October Ventures. Following a debut season that sold out all six events and generated 2B views, IDL will use the funding to expand its tour, strengthen team and dancer operations, improve broadcast production and develop new fan experiences for 2027. - learn more
            • Santa Fe Springs-based DrizzleX raised a $6.8M Series A-2 led by Israel Investment Fund Group, with several of the water-management platform’s own customers also investing. The company will use the funding to expand sales, streamline hardware manufacturing, build partnerships and develop new products that help property owners detect leaks, reduce water use and lower operating costs. - learn more
            • POV Beauty raised an undisclosed Series A led by Silas Capital, with participation from RÉDO Capital and existing investor Imaginary Ventures. The skin-prep brand will use the funding to build on its nationwide Sephora launch, expand its team and TikTok Shop presence, and develop more skincare-makeup hybrid products. - learn more

            LA Venture Funds
            • Chapter One participated in Warp Sciences’ $215M Series A, which was led by Lightspeed and included a large group of venture firms and angel investors. The company is building AI-powered, increasingly automated laboratories that will manufacture and test molecules for drug developers, aiming to accelerate preclinical research while expanding scientific infrastructure in the U.S. - learn more
            • Capital Group participated in Legora’s $550M Series E, which was led by Atreides Management and valued the legal AI company at $8.8B. Legora will use the funding to expand across the U.S. and international markets while developing new capabilities for its agentic operating system, which is used by more than 140,000 legal professionals. - learn more
            • Group 11 participated in CapitalOS’ $21.9M Series A, which was led by LGVP and included WEX Venture Capital, Great North Ventures and Night Capital. CapitalOS will use the funding to scale its infrastructure, which enables B2B software platforms to quickly offer financial products while outsourcing functions such as compliance, risk management and underwriting. - learn more
            • Starshot Capital participated in IMIO’s $12M funding round, which was led by Sofinnova Partners and included Chipotle’s Cultivate Next, Grow Together Salinas, Earth Foundry and Serra Ventures. The agricultural biotechnology company will use the capital to build a Chicago headquarters, laboratory and manufacturing facility for its freeze-dried microbial products, which are designed to improve soil health and crop yields. - learn more
            • SUM Ventures participated in Vectorial’s $3M seed round, which was co-led by Smilegate and SenseAI Ventures and included several investors connected to UC Berkeley and Stanford. The startup will use the funding to scale its AI-powered consumer research platform, which lets companies test products, marketing campaigns and AI agents against simulated audiences before launching them publicly. - learn more
            • Wave Function Ventures participated in Stellios Technologies’ oversubscribed $5M pre-seed round alongside Sofreh Capital, Cubit Capital, Mana Ventures, Atoms & Bits and other investors. The Austin-based company will use the funding to deliver its first high-power microwave systems, establish domestic research and manufacturing facilities, grow its team and advance technologies spanning directed energy, compact fusion and next-generation propulsion. - learn more
            • Upfront Ventures participated in Daytona’s $60M Series B, marking the Santa Monica firm’s third investment round with the company. Led by FirstMark Growth, the financing valued Daytona at $1B and will help the startup expand sales and engineering for its cloud infrastructure, which provides secure virtual computers where AI agents can execute tasks. - learn more
            • Core Innovation Capital participated in Delegance Brokerage’s $3.1M pre-seed round, which was led by Grit Capital Partners and included Gilgamesh Ventures and Outside VC. The AI-powered commercial insurance brokerage will use the funding to hire licensed brokers and engineers and expand partnerships as it promotes a flat 5% fee model in place of traditional commissions. - learn more
            • Core Innovation Capital participated in Prism Data’s $20M Series A, which was led by Story Ventures and included FINTOP Capital, Obvious Ventures, 1st & Main Growth Partners and Mana Ventures. Prism will use the funding to expand its cash-flow underwriting technology, AI infrastructure and data science team while growing across the U.S. and Canada and preparing for international expansion. - learn more

            LA Exits

            • Sanctuary has been acquired by WSG Brands, adding the contemporary women’s label to a portfolio that includes Von Dutch, Nasty Gal and Allbirds. The purchase price was not officially disclosed, though earlier documents placed it at $67M; WSG plans to expand Sanctuary internationally and into new categories, while founders Ken and Debra Polanco will remain involved. - learn more
            • SecureNet Solutions was acquired by CompassMSP, expanding the managed IT and cybersecurity provider’s presence on the West Coast. The deal gives SecureNet’s real estate, healthcare and professional services clients access to CompassMSP’s national cybersecurity, compliance and advisory resources while retaining their existing service team; financial terms were not disclosed. - learn more

              Download the dot.LA App

              RELATEDEDITOR'S PICKS
              Trending