Nasdaq’s Adena Friedman on the Power of Going Public

Spencer Rascoff

Spencer Rascoff serves as executive chairman of dot.LA. He is an entrepreneur and company leader who co-founded Zillow, Hotwire, dot.LA, Pacaso and Supernova, and who served as Zillow's CEO for a decade. During Spencer's time as CEO, Zillow won dozens of "best places to work" awards as it grew to over 4,500 employees, $3 billion in revenue, and $10 billion in market capitalization. Prior to Zillow, Spencer co-founded and was VP Corporate Development of Hotwire, which was sold to Expedia for $685 million in 2003. Through his startup studio and venture capital firm, 75 & Sunny, Spencer is an active angel investor in over 100 companies and is incubating several more.

Nasdaq’s Adena Friedman on the Power of Going Public

Adena Friedman is president and chief executive officer of Nasdaq, which operates the second-largest stock exchange in the world by market cap. Named one of Forbes' most powerful women, Adena built her career at Nasdaq, starting as an intern straight out of an MBA program. Outside of a three-year stint as chief financial officer at The Carlyle Group, she's been with Nasdaq ever since. In this episode, Spencer joins Adena in New York City to discuss the power of mentorship, the future of the U.S. capital markets and why going public can spark innovation.


Press Play to hear the full conversation or check out the transcript below. You can also subscribe to Office Hours on Apple Podcasts and PodcastOne.
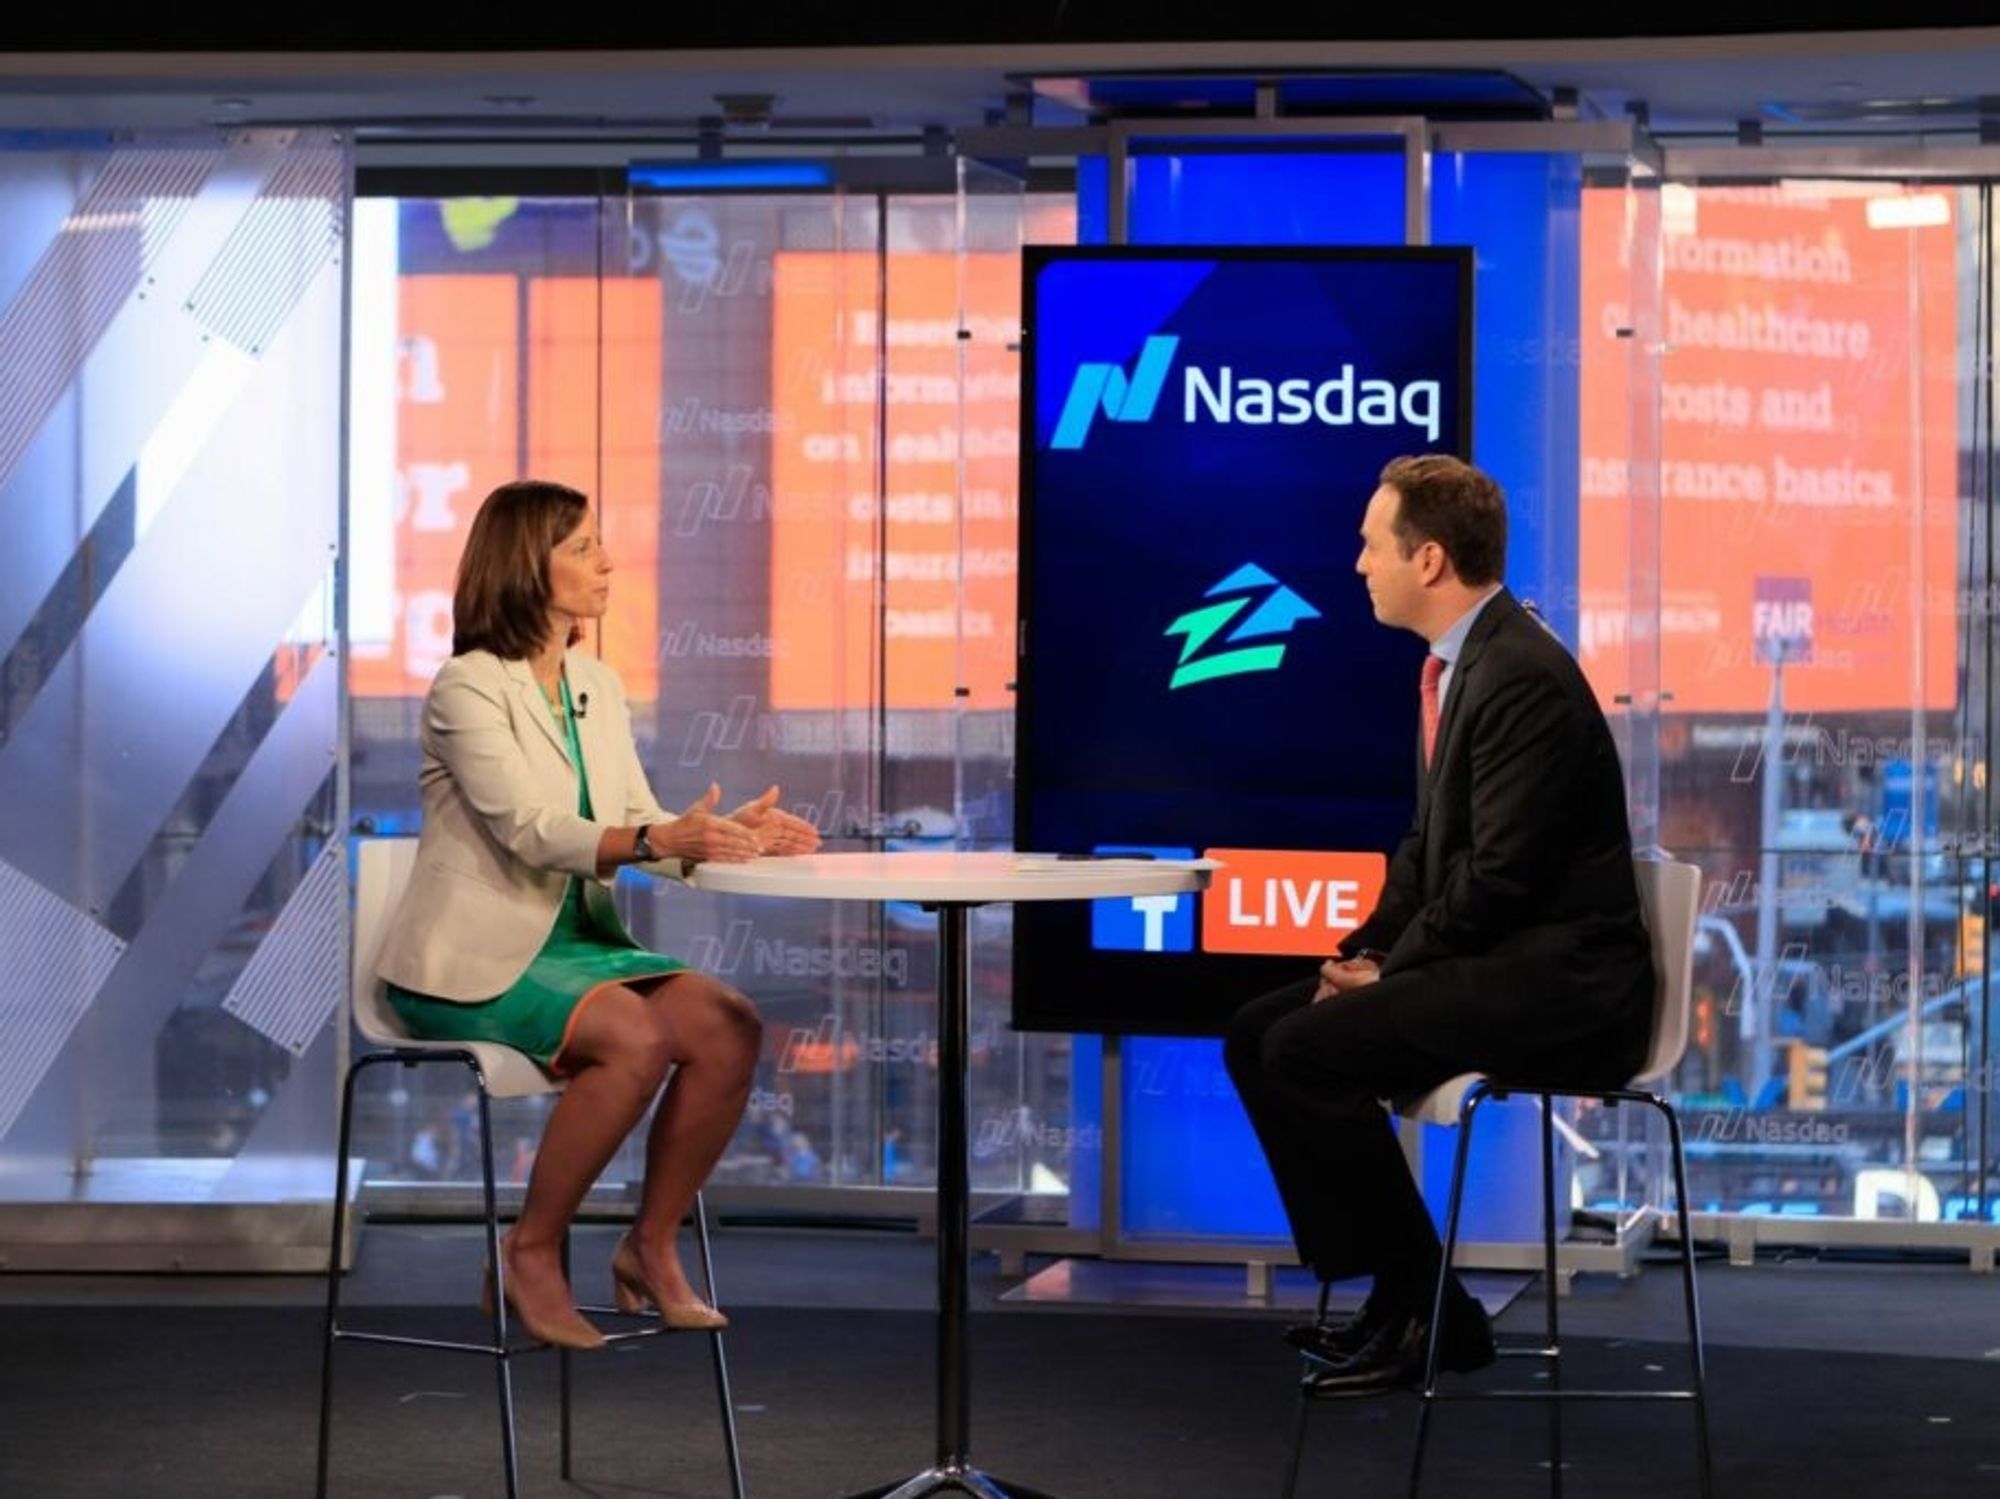
Spencer Rascoff: I'm in Times Square today at the Nasdaq market site with Adena Friedman, CEO of Nasdaq. Hi, Adena. How are you?

Adena Friedman: Fine, how are you?

Rascoff: Great. Firstly, a lot of listeners might not fully understand the size and scope of Nasdaq. So, explain to people, what is Nasdaq?

Friedman: Sure. Well, Nasdaq today is a global technology company that serves the capital markets, and we serve our capital markets by operating exchanges ourselves in the U.S. and the Nordics, but we also provide the technology that powers over 90 other exchanges around the world.

And then we take all of the data and analytics that are generated off of our exchanges as well as other information that we gather, and we provide a lot of insights and analytics to all of the customers in the capital markets, whether they're corporate clients or investment management clients or, obviously, the broker-dealer clients. We feel just so fortunate to be in the center of the capital markets globally today.

Rascoff: And the revenue model is one where issuers — so, companies that trade on these exchanges — pay, or people that buy and sell the stocks pay?

Friedman: Right. So, we basically have — we generate revenue in lots of different ways, but one of the sources of revenue is the listing fee. So, companies who choose to list on Nasdaq pay an annual fee to Nasdaq. We then generate trading revenue not only in our equities business from the trading of those stocks, but also in our options and futures businesses here and in the Nordics.
And then we also generate a lot of information coming off the trading engines, and that information we then sell to give people transparency into what's happening in the markets. That also is a revenue stream.
We then have our index data. We create a NASDAQ 100. We have $150 billion of assets under management tied to our indexes, and that's a revenue generator. And then we provide software and services to corporate clients as well as to other exchanges around the world and broker-dealers, and so that's a technology product base that we have revenue off of as well.

Rascoff: A much more diverse revenue stream than most people realize. So, let's talk a little bit about your career. You started as an intern at Nasdaq.

Friedman: I did.

Rascoff: When was that, if you can tell us?

Friedman: Sure. I came right out of business school, and I did an internship at Nasdaq in 1993 over the summer. At the end of the year, I took a permanent position. And so it was very, very fortunate that I had a chance to be here at the start.

Rascoff: And what was your career path like during that, I guess, two-decade stint? And we'll cover when you left and then returned in a moment.

Friedman: Sure. Well, Nasdaq at the time was a subsidiary of an organization called the National Association of Securities Dealers, which is now FINRA. And so it really was really early in its existence. It had been around for 22 years, but it was still growing up as a marketplace.
And so I really had an opportunity to come in early and be part of the trading operation and the trading organization and help them look at the trading products that they were offering out to broker-dealers to make sure that they were, in fact, optimizing them for their business.
Since NASD was a nonprofit organization and Nasdaq was a for-profit subsidiary, it was an interesting balance in terms of what they were there to do and yet realizing that they actually had these great products that they could optimize from a revenue perspective.
So, I got a chance to write business plans and then become a product manager for some of these products before I then took on the data business.

Rascoff: And we talk a lot at Zillow Group about career development and career pathing. Sheryl Sandberg in “Lean In" — on this podcast she talks, of course, about how career development is more like a jungle gym than a career ladder.
What was your path like during that time? Was it a straight-and-narrow, up-and-down ascent, or did you have detours that took you into different areas around Nasdaq? Describe what that was like.

Friedman: Sure. Well, I would say that it was a jungle gym within the groups that I was in. There was no set career path for me. There was nothing in Nasdaq that had job families. It was very much still a very, what I call, “organic organization" in terms of looking at how to develop your career.
So, I just got very fortunate because when I — every two years early in my career, I just found a new opportunity that would take me up a rung. Or in one case it was sideways, but honestly it then propelled me forward from there.
And I had a few times when I had to look around, and I said, “Wow, should I go and really focus in on marketing, or should I go take this product management job?"
And I had great mentors and sponsors within Nasdaq that really said, “Adena, you are someone who really likes to run a business. You should become a product manager. The marketing job is interesting, but it's not really — it doesn't play to your strengths as well as this other thing." So, I was able to move up through the organization but really with a lot of sponsorship.

Rascoff: One of those sponsors that you talk about is Bob Greifeld, who was the CEO, who recently retired from Nasdaq. What was that relationship like? How should somebody seek out a mentor or a sponsor and get the most out of that relationship?

Friedman: Sure. Well, I do think my personal opinion is that both sponsorship and mentorship — it very much has to be a natural activity. You can't force a sponsor or force a mentor on someone. I think that you, though, have to curate and develop that relationship.
When it comes to mentoring, I think it's an easier thing to curate where you start very casually, and you say, “Well, gosh, I really admire this person," whether that's a person inside the organization or outside the organization. If you ask them to have coffee with you one day, and you give them enough notice, most of the time they're gonna say yes.
Then once you have that coffee or have a meal, and you realize you have a good connection with that person, and they're giving you good advice, and they feel good about the advice they're giving you, they're likely to do it again. And if they do it again, then you have established yourself with someone who you can rely on to help you.
When it comes to sponsorship, most of the time those are people who are in a position of power to guide your career, and they can either be a positive or a negative sponsor. In my case, I was very fortunate. I actually had three sponsors in my career, and I think that all of them were really helpful in not only just putting me in the room and giving me the opportunity, but also guiding me, like that decision around product management versus marketing.

Rascoff: Is that something that Nasdaq in particular focuses on creating and cultivating a culture of or that sponsorship and mentorship is something that you created and owned on your own?

Friedman: It definitely was on me, and frankly, at the time you don't even realize you're getting sponsorship, right? So, with mentors, I do feel like you are realizing that you're going in and touching other people and asking them for their advice. But with sponsorship, you're just — it's so natural that you realize, “Wow, that person just really helped me out." So, it was much more organic than it was planned.
I think Nasdaq has definitely developed its mentorship program, but to me sponsorship really needs to become — it needs to be a naturally developed thing. It's somewhat the responsibility of the employee and of the manager.

Rascoff: So, after many years at Nasdaq , you left to go become CFO of Carlyle Group, a private equity firm, when it was still private with the intention of going public. Why did you leave, and what was that experience like at Carlyle for the, I think it was, three years that you were there?

Friedman: Right. So, I was the CFO at Nasdaq and actually was having a great time and loving my job, and I got a cold call, which I never take cold calls from recruiters. But in this particular case, he got my attention because he did say it was Carlyle. And at the time I —

Rascoff: So, a note to recruiters, by the way, 'cause I get a lot of calls from recruiters too. It's usually super anonymous and vague. It's like, “It's a leading industrial company. I can't tell you who it is." So, maybe recruiters should be a little bit more transparent to get the return call.

Friedman: Exactly. And it was funny because my family lives in Washington, D.C., and I had been commuting to New York for many, many years. I had gotten very used to it. So, it was very much part of our lives. But at the same time, Carlyle is the really premier financial institution in Washington, D.C. It's an organization that I knew well. I knew some of the people there. I had a huge admiration for the company.
And so, he really had no idea that I lived in D.C., but when he called, I said, “Well, do you realize that I live in Washington, D.C.?"
And he said, “Wow, that's fortunate." So he laid out the opportunity, and really, the opportunity to be the CFO of a leading financial institution like Carlyle, to help them go through the process of becoming a public company and really thriving as a public company, was incredibly compelling.
At the time, I'd been at Nasdaq for 17 years, and I felt that if I was going to try something different, this was the one opportunity that presented itself that seemed like the right one to take. So I left and went to Carlyle for three years, and I had a great experience there.

Rascoff: Now when you told your colleagues at Nasdaq— I guess, was Bob the CEO?

Friedman: He was, yeah.

Rascoff: When you told them that you were leaving to go to Carlyle, what was their reaction like?

Friedman: Bob was incredible, actually. He and I have always had a very close partnership. He has been a great sponsor to me, and he recognized at that time with the situation with the age of the kids and the opportunity that was in front of me — it just seemed like it was the right thing to do.
And so, he was very supportive. Really supportive. And he could have chosen not to be. But he really was supportive and said, “That's the right thing for you to do, Adena. Go for it."

Rascoff: And I'm sure the class that Nasdaq handled the situation with factored into your decision to return several years later.

Friedman: Of course, of course. My personal belief is that — I call them boomerang employees. I think boomerang employees can be great, great employees because there are a few reasons for that. One is they go and they experience another part of the industry, and they learn a lot.
The second is that is that they then become a client, and you then get to maintain that relationship with them as a client. And the third thing is that when they do come back, they realize what they missed.

Rascoff: Right.

Friedman: And we do have a fair number of boomerang employees because they realize what a great environment Nasdaq is and what a special place that Nasdaq has in the financial industry, and they become even more loyal to the company when they get back.
But at the time I left Nasdaq, I had no expectation of ever coming back. When I make a decision, you say, “Well, gosh, what do I want to be for the next 15 years," and thinking about the opportunities at Carlyle were really, really exciting to me. So, I left with the intention of spending at least the next 10 to 15 years there.

Rascoff: On the topic of boomerang employees, there's a company that I did a summer internship at when I was in college called Bloomberg — that you know well — that famously does not allow boomerang employees. When you leave Bloomberg, you cannot return — with one exception, which was they let Mike Bloomberg come back. But his name is on the door, and he had left to become mayor.

Friedman: And perhaps he had a lot of equity ownership in the company.

Rascoff: So, they let Mike back, but other than Mayor Bloomberg, they don't let employees return. It's the only company I'm aware of that has a policy like that. But they actually think that's very important to their culture. It seems that you disagree. I also disagree. We welcome back boomerang employees.
But it's something that I've spent a lot of time thinking about because on the way out the door, it does — it certainly gives somebody much greater pause. A tech company like ours, we have people leave not infrequently to go try a startup, and sometimes their attitude is, “Well, if the startup fails, in a year I can always come back." As a manager, that's very difficult for me to let that person leave.

Friedman: Well, and my view on that one is it's totally up to you as to whether you let them come back. They have to make a determination that they're leaving with the intention of not coming back because if they assume they can come back, that may not be an opportunity. First of all, the company may have moved on. Second of all, they may have found someone better, frankly, to replace you. And third of all, you have to be coming back for the right reasons. You can't be coming back as a default.
That's up to the manager to understand what is driving that employee to come back to Nasdaq. Is it because, “Oh, well, they failed at the other thing, so they might as well come back"? Or is it, “Wow, I really miss Nasdaq, and I really can't wait to be one of your best employees ever"? Right? And so, I think it's up to the manager to make that determination, but you certainly shouldn't assume that you have that opportunity.

Rascoff: Right. So, when you decided to leave Carlyle and return to Nasdaq, what went through your mind at that point? Why did you make that decision?

Friedman: Well, so, a few things. The first thing was that I had been a CFO for five years at that point, and while I really enjoyed the role and I really enjoyed learning how to be the lead risk manager in the company as well as to build out the operations — the finance operations for Carlyle and before that for Nasdaq— I really missed the customers.
I had been running a business up until the point I became the CFO of Nasdaq, and I really missed the pressure and the fun of running a P&L and having that client interaction and being able to drive a company forward or drive a business forward.
And so, when Bob came back and said, “Well, why don't you come back as our president, and you can run these certain businesses," it was an incredibly exciting opportunity for me to get back into that P&L responsibility and to take on such a large part of the Nasdaq ecosystem.
So, it was just a huge opportunity. And I really, really enjoyed Carlyle a great deal, but I saw this as the better opportunity for me at that time.

Rascoff: And I would be a terrible interviewer if I didn't ask: When you took Carlyle public, did they end up listing on Nasdaq?

Friedman: They did, actually, and it was really interesting. We went through a full, what I call, “bake-off process." We had both of the companies come in twice. I just got to be a fly on the wall and watch each of them do their pitch. So, it was actually really, really fun.
I tried very hard not to be a part of the decision process, 'cause it really was up to the founders to make that determination. It was fascinating to see how they came at it so differently.

Rascoff: I'm sure that makes you a better CEO of Nasdaq now having been on the client side.

Friedman: Yeah. I'd say certainly going through the process of going public has made me — it really, really informed me in terms of what we could do at Nasdaq to make it a better experience, to help manage the client through that experience and then to realize just how hard it is. We are here to make companies' lives easier, and so what can we do as the exchange to make that process for our customers?

Rascoff: So, a perfect segue into Project Revitalize, which is a project that's important to you. It's something that you and I talked about at the Microsoft CEO Summit.

Friedman: That's right. I'm glad you remember.

Rascoff: I don't know if you had actually formalized it as a full initiative at Nasdaq at the time. But for our listeners, the basic issue here is there are, I think, half as many public companies today as there were a decade or two ago.

Friedman: That's right.

Rascoff: And many fewer IPOs. Of course, that's bad for Nasdaq's business, but it's also bad for the economy. It's bad for innovation. It's bad for the country, the world. There are a lot of different reasons why, and I think reasonable people disagree on the specific reasons.
But you're spearheading a group of initiatives at Nasdaq to try to address this. Why don't you describe what you're working on?

Friedman: Sure. Well, I think the first thing is we had to determine that there really is a problem. I think that we have been seeing this problem manifest itself over a long period of time, and so therefore you don't realize necessarily each year that you go through it that there is a growing issue.
But I would say that over the last three years, it's really culminated into something that's a known issue today, which is that over time the government has placed so many requirements on companies as public companies and the process of going public has become so much more challenging, the nature of investors has really become very different and that the environment around being a public company is very different today than it was 10 and certainly 20 years ago.
And so, we have been looking at what are the things that we can do to advocate on behalf of companies to make sure they find that the process of going public and being public is actually an inviting process and something that they want to pursue?
So, why do we care, and why should anyone who is listening to this care? The first thing is that 86 percent of all job growth in the United States since 2000 has come from companies after they have gone public. So, when we look at the companies before they're public and after they're public, 86 percent of the job growth came after they went public, and that's just in the last 17 years. If we look over a longer period of time, it's over 90 percent.

Rascoff: Partly because being public provides them with access to permanent capital, which allows them to grow. And so, if they're not able to get public, there won't be as much job growth.

Friedman: That's right. So, the whole purpose of going public is to give you access to growth capital. It's really a shot in the arm to allow you to grow and expand your business, and so if you don't have that now people say, “Yes, but there's so much private capital out there. It's so readily available. Why do I need to tap the public market so I can grow that way?"
And for some companies, and a very small subset of companies, that is, in fact, true that they can use private capital to do that. But for the majority of companies, they really still do have to ultimately access public capital to really get the amount of capital they're looking for. I think that we are assuming that that's available to everyone in the private markets, and it's not.
The second thing to realize is that when companies do access private capital, and they have all of this ability to grow using private capital, well, where is that private capital coming from? And I come from private equity. I'm a huge believer in private capital as being part of the ecosystem.
But that private capital is being made available to the wealthiest in the country, right? It's the wealthiest in the country that are generating that private capital and making it available to those companies, which means the vast majority of retail investors don't get access to these growth companies until they go public.

Rascoff: So when Microsoft went public in — when did Microsoft go public, in the early '80s, I think?

Friedman: Mid-'80s, mmm hmm.

Rascoff: Another $500 billion in market capital was created over the ensuing 30-plus-year period.

Friedman: That's right, and Amazon went public. They were $300 million in valuation, and they're now $400 billion. Another great company actually was Applied Materials that was here yesterday. So, they went public in 1972, the first year that Nasdaq existed. At that time, they were generating maybe $10 million in revenue, and today they are generating $14 billion in revenue.

Rascoff: And so, all of that appreciation accrues to investors, whether they be institutional investors or retail investors. It's egalitarian.

Friedman: Or retail. It makes it so that every investor gets to access it as opposed to a subset of investors. I think that private capital providers will say, “Yes, but we represent pensions," and that's totally true. But the average retail saver does not get access to those investments.
And I think it's really in our — I think it's frankly the government's responsibility, and it's Nasdaq and every exchange's responsibility to try to find a way to make the public markets more inviting for companies. So, we have a whole range of changes that we would like to see and that we will be strongly advocating for and pushing to make sure that we create a more inviting environment.

Rascoff: What types of things are those?

Friedman: So, we looked at disclosure obligations for companies as to what we require that they disclose every quarter and whether or not everything should have to be disclosed every quarter. We looked at proxy access and, frankly, how challenging it is to have these very, very small investors to have total access to your proxy.
There is some very large percentage of proxy reform proposals that are being generated by about four investors who just buy up the minimum amount of shares, and then they go out and they agitate. So, is that really what proxy access is all about?
Proxy firm reform. The ISS and Glass Lewises of the world, should they have to have more regulation and oversight to make sure that they're doing the right thing for the companies and the investors?

Rascoff: So, just on disclosure, do European companies only report twice a year and not four times a year? Do I have that right?

Friedman: It depends on the country. So, in the UK, that is absolutely true. They have an obligation to report a full report twice a year, and then they do these interim reports the other two quarters. I think that's a good model to consider.

Rascoff: You would advocate for that or advocate for evaluating that at least?

Friedman: Yeah. In fact, that's one of the things we said in there. There's also tax reform and things we can do on the tax side. There is, in fact, litigation reform to make it so that companies have a fairer environment when they're dealing with shareholder class action suits.
And then I think that then there's market structure. So, is every company being treated the right way in the public markets with a one-size-fits-all market structure, and should we be looking at a market structure that really is more tailored to smaller companies versus larger companies?

Rascoff: So, by that you mean, for example, different disclosure requirements for smaller companies than larger?

Friedman: Yeah, different disclosure requirements, but also different market models.

Rascoff: Okay. Wow, well, a lot to think about there. Obviously we went public relatively early as a company. We had $15 million in quarterly revenue, and people thought that was perhaps too small to go public. We went public with about a $500 million market cap, and we really followed that — it's quaint. You're right. People don't tend to do that anymore.
Now, most of the appreciation that has occurred at our company has accrued to public market shareholders, not private market shareholders, because we went public relatively early. In Zillow Group's case, it has been hugely successful and the right decision to have gone public early.

Friedman: Just using Zillow, for example: One of the great things about Zillow is that your users can now be shareholders, right? So, your users can be owners, and they understand your product. They understand it deeply because they use it.
So, they also understand the potential of it. They can really get involved and engaged in understanding what benefit they're getting, and therefore they can understand why this company is gonna be a growth company, right? So, it actually has been a great success story.

Rascoff: Thank you for the conversation, and thank you for being our exchange. Zillow Group proudly trades on NASDAQ. And thanks for having me today.

Friedman: Well, thank you so much. It was really a pleasure. Thank you.

The post Nasdaq's Adena Friedman on the Power of Going Public appeared first on Office Hours.
https://twitter.com/spencerrascoff
https://www.linkedin.com/in/spencerrascoff/
admin@dot.la
Northwood’s Nine-Month Rise to $2B
Northwood

🔦 Spotlight

Happy Friday, Los Angeles.

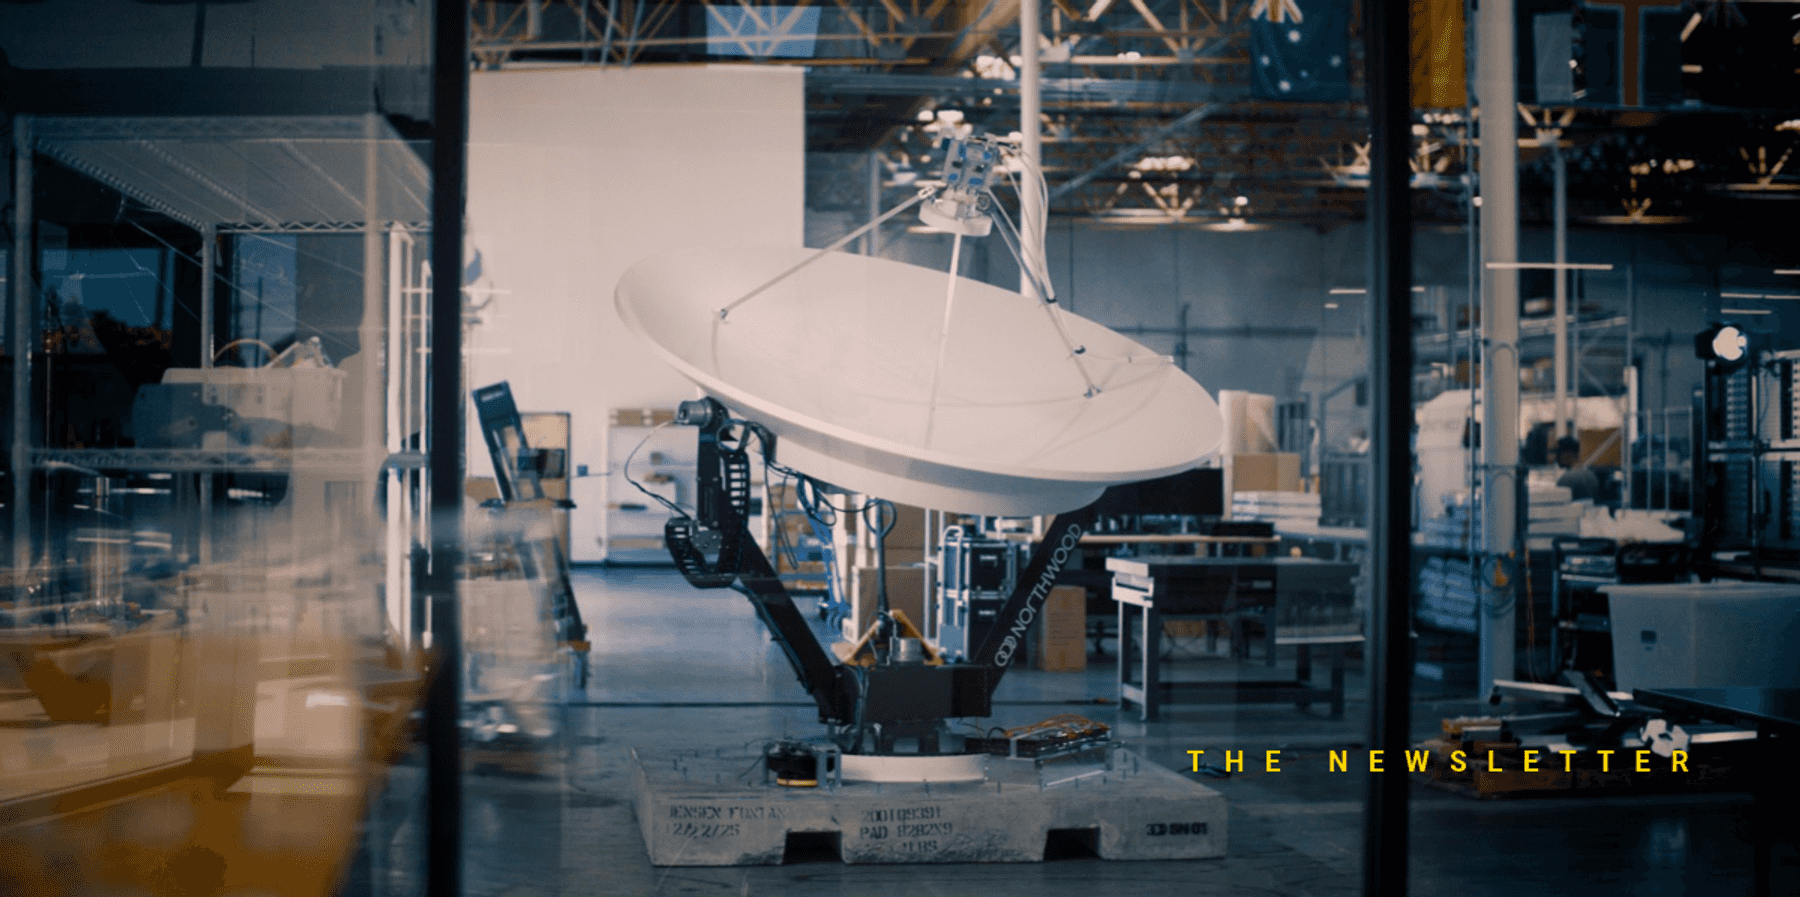
Nine months ago, Northwood Space was operating from a 35,000-square-foot facility in Torrance. Today, it occupies a factory more than five times the size, has deployed six ground sites across two continents and is reportedly worth $2B.

Aerospace companies are not generally known for moving this quickly.

When dot.LA last covered Northwood, the company had just raised a $100M Series B and secured a nearly $50M contract with the U.S. Space Force. The deal established Northwood as one of the more closely watched companies working on the essential infrastructure that keeps satellites connected to Earth.

Less than a year later, Northwood is operating at a considerably different scale.

The company announced this week that it raised a $375M Series C co-led by Andreessen Horowitz and DFJ Growth, with additional investment from Washington Harbour Partners, Alpine Space Ventures, StepStone, In-Q-Tel and others. The round values Northwood at a reported $2B. A separate credit facility from HSBC Innovation Banking will provide additional support for working capital and network expansion.

The financing is notable. What Northwood accomplished between rounds is the more interesting part.

Since January, the company has deployed six ground sites across two continents, demonstrated communication with a government satellite in geosynchronous orbit and introduced a high-throughput antenna system for moving larger volumes of data. It also opened a 185,000-square-foot headquarters and factory in Torrance, expanding its manufacturing footprint more than fivefold.

Northwood now employs more than 140 people and plans to add 400 jobs across Torrance and Washington, D.C., over the next three years.

The company builds the infrastructure that allows satellites to exchange commands and data with operators on Earth. Rather than requiring every satellite company to develop its own ground stations, Northwood is creating a shared network that commercial operators and government agencies can access as needed.

Think cloud infrastructure, except the servers are antennas and adding capacity requires considerably more than clicking a button.

That distinction matters. Software companies can often scale by purchasing additional computing power. Northwood must manufacture physical systems, establish sites around the world and reliably serve customers operating across multiple orbits.

Its new Torrance factory is central to that plan. The facility is designed to produce hundreds of antennas each year, giving Northwood the manufacturing capacity to expand its network faster than traditional ground infrastructure can typically be built.

Demand is moving just as quickly. The number of active satellites worldwide grew from roughly 3,000 in 2020 to more than 14,000 by the end of 2025. Every one of them eventually needs to send information somewhere, and existing ground networks were not designed for the volume of missions now entering orbit.

Northwood’s previous funding helped prove it could build the technology and win serious customers. This round is about turning that early progress into global infrastructure.

The question is no longer whether Northwood can build a modern ground network. It is whether the company can make Torrance-built hardware the default connection layer for a rapidly expanding space economy.

With another $375M behind it, that test begins now.

More from this week’s LA startup and venture scene below.

🤝 Venture Deals

    LA Companies

    • Guava, a Los Angeles-based developer platform for building AI voice agents, raised a $12.5M seed round led by Acrew Capital, with participation from Flourish Ventures, WillowTree Ventures, Clocktower Ventures and existing investor Commerce Ventures. The company will use the funding to further develop its voice AI models and products while building a go-to-market team focused on enterprises and business process outsourcing providers. - learn more

    LA Venture Funds
    • Blue Bear Capital participated in Ocient’s $100M Series C alongside Greycroft, In-Q-Tel, Buoyant Ventures and other existing investors, while BOKA Capital and OCA Ventures co-led the round. The data analytics and AI infrastructure company will use the funding to expand OcientAIQ, its platform for delivering fast, reliable answers from petabyte-scale datasets, and bring its technology to more customers globally. - learn more
    • Mystic Ventures participated in Siggy’s $6M pre-seed round, which was led by Village Global and also included PsyMed Ventures, Coalition Operators and several angel investors. Founded by veterans of Nurx and Journey Clinical, Siggy combines AI, wearable data and licensed clinicians to monitor patients between mental health appointments, with the funding supporting product development, regulatory work and hiring across its clinical and engineering teams. - learn more
    • Grid Capital and Thin Line Capital participated in Strive Robotics’ more than $3M pre-seed round alongside Tenon Ventures, with Hi Ventures leading the financing. The Cambridge-based startup develops adaptable robots that can learn complete manufacturing workflows and operate existing factory equipment, with the funding supporting product development, hiring and early customer deployments. - learn more
    • Sum Ventures participated in Circularity Fuels’ $7M seed round alongside Automotive Ventures, with DCVC and Trucks Venture Capital co-leading the financing. The company converts dairy biogas into sustainable aviation fuel and will use the capital to build a demonstration plant, design its first commercial facility and begin licensing its reactor technology to outside partners. - learn more
    • Griffin Gaming Partners participated in EloElo Group’s $80M Series C alongside MIT Investment Co., Play Ventures, Kalaari Capital and WaterBridge Ventures, while Hornbill Capital and NBCUniversal co-led the round. The Bengaluru-based entertainment company will use the funding to produce more original microdramas across multiple languages, expand its Story TV platform internationally and continue developing Dolphin AI, its AI-powered creative suite. - learn more
    • Mucker Capital participated in Lazarus AI’s $43M funding round alongside QBE, State Farm Ventures, Wave Function Ventures, Techstars and several other investors. The Boston-based company develops AI systems for enterprises and government agencies that retain control over their data, models and deployment, with the new capital supporting research and development, strategic partnerships and new product launches. - learn more
    • Alexandria Venture Investments continued its support of Thryv Therapeutics by participating in the company’s $30M Series B, which was led by InClin and included several other existing investors. The clinical-stage biotech will use the funding to launch a Phase 2a study of THRV-1268 in patients with heart failure and evaluate the drug’s safety and potential effects on cardiac function and arrhythmia risk. - learn more
    • Supply Change Capital led Kodiact’s $2.5M pre-seed round, with participation from Green Circle Foodtech Ventures and Velocity Catalyst. Kodiact helps manufacturers anticipate raw-material price swings and simulate sourcing decisions, and will use the funding to expand its market data and AI capabilities, grow enterprise deployments and enter additional industries including cosmetics, packaging and chemicals. - learn more

      Download the dot.LA App

      Anduril Built Fighter Jets. Now It’s Making a Laptop.
      Anduril

      🔦 Spotlight

      Happy Friday, Los Angeles.

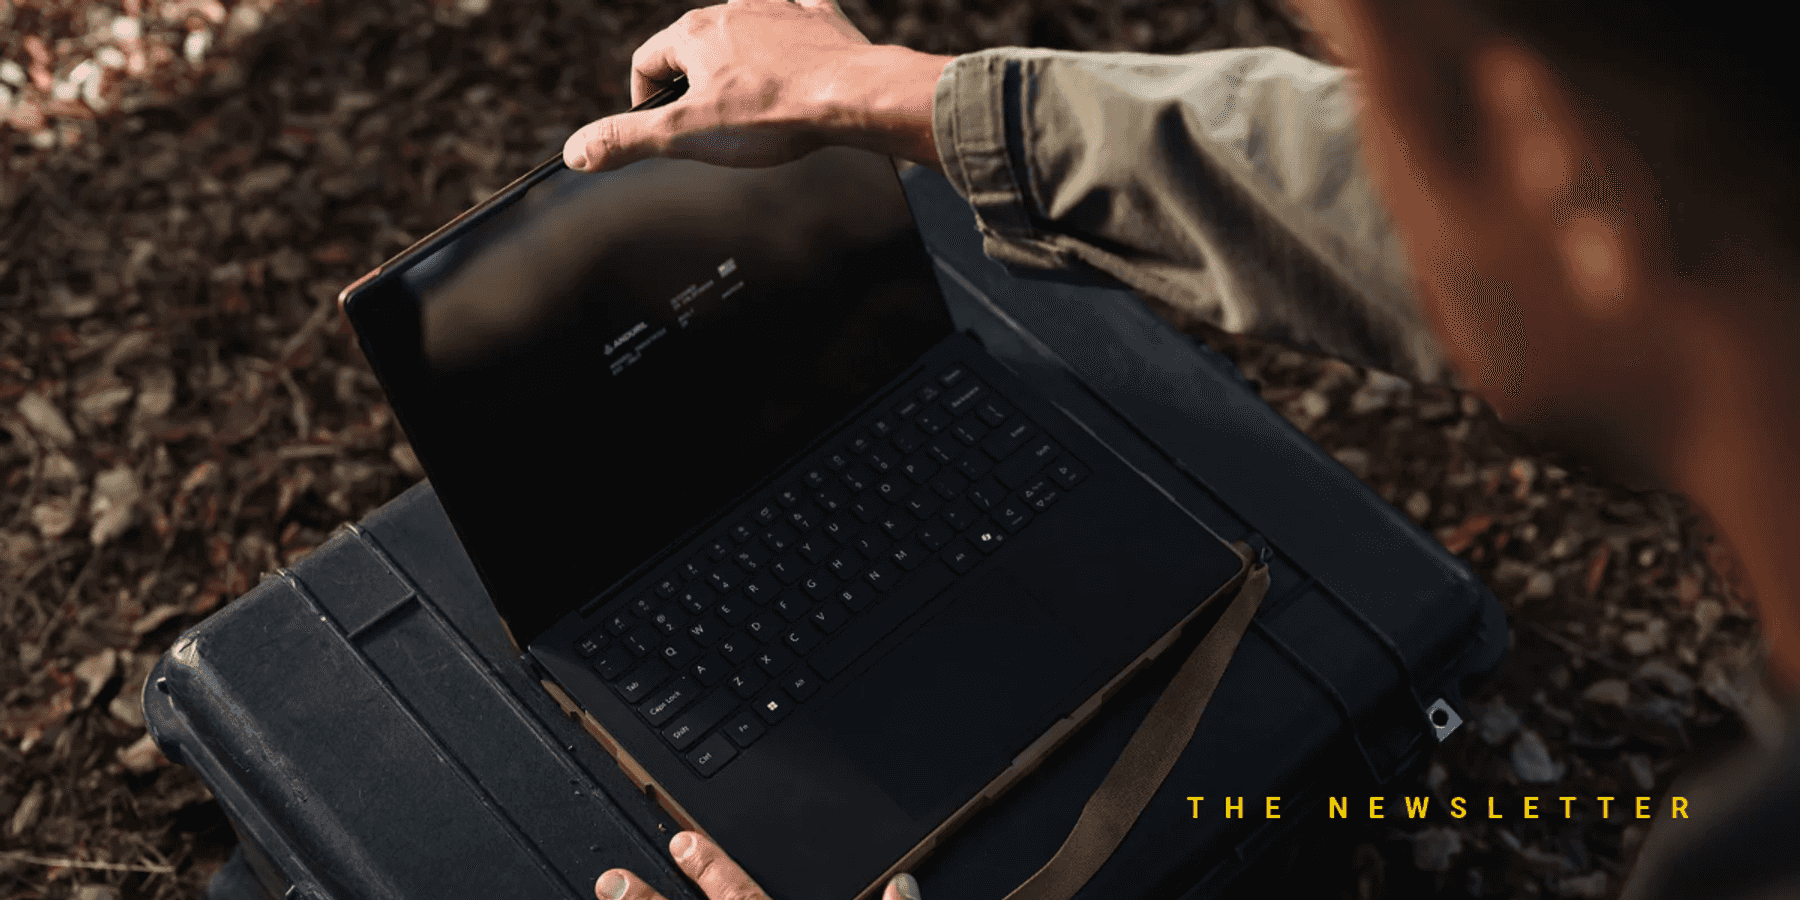
      Anduril has built autonomous drones, underwater vehicles and fighter aircraft. Its newest product is considerably more familiar.

      A laptop.

      The Costa Mesa-based defense technology company announced this week that it is partnering with San Diego-based Qualcomm Technologies to launch BlueChip, a new line of computers designed in California and manufactured in the United States.

      The first product will be a rugged laptop powered by Qualcomm’s Snapdragon X Series platform and built for customers in government, defense, public safety and other critical industries. Anduril has already produced working prototypes and plans to begin accepting orders in 2027.

      At first glance, a laptop may seem like a modest addition to a company known for developing autonomous military systems. But BlueChip is less about entering the crowded consumer-electronics market and more about rebuilding the industrial foundation behind the machines Americans use every day.

      The United States remains a leader in designing advanced technology, but much of the physical production required to turn those designs into finished computers has moved overseas. That includes not only semiconductor manufacturing, but also circuit boards, displays, batteries, enclosures and the network of specialized suppliers that connects them.

      For most consumers, that dependency is largely invisible. For the government and military, it represents a potential vulnerability.

      BlueChip is Anduril’s attempt to close that gap.

      Components sourced from the United States and allied countries already account for more than 90% of the prototype laptop’s procurement cost. Circuit-board assembly is planned for Anduril’s Arsenal-1 facility in Ohio, while the company develops domestic production capabilities for enclosures, batteries and other hardware.

      The goal is to gradually replace remaining foreign dependencies and create an end-to-end American computer supply chain that can support additional products beyond the first laptop.

      That process requires more than moving an existing design into an American factory. Anduril is redesigning the computer around what domestic manufacturers can realistically produce at scale. The work includes selecting machinable American metals, adapting power systems to available battery technology and developing a bonding process for domestically made display glass.

      In other words, Anduril is not simply assembling a laptop in America. It is working backward through the supply chain to make American assembly possible.

      Qualcomm will supply the computing foundation. Its Snapdragon X platform will handle processing, graphics and on-device artificial intelligence, giving BlueChip users the ability to run certain AI models locally rather than sending sensitive information to the cloud.

      That is particularly valuable for government and defense customers operating in secure environments, but it also reflects a broader shift in computing. As AI becomes embedded in everyday workflows, the location where information is processed may become nearly as important as the model doing the processing.

      The partnership also reinforces Southern California’s growing role in the effort to rebuild American advanced manufacturing.

      Anduril remains headquartered in Orange County, but its regional footprint is expanding. The company is investing $1B in a new campus spanning Long Beach and Lakewood that is expected to support approximately 5,500 jobs and include engineering, laboratory and prototype-manufacturing space.

      Qualcomm, meanwhile, has spent decades building San Diego into a center for wireless technology and semiconductor design.

      BlueChip brings those two Southern California strengths together: Anduril’s ability to move quickly from engineering concept to physical product and Qualcomm’s expertise in efficient, high-performance computing.

      The first BlueChip laptop is not intended to compete for space in every backpack or coffee shop. Its early customers will likely be institutions that care deeply about security, reliability and control over their technology supply chains.

      But the larger ambition reaches far beyond a single device.

      If BlueChip succeeds, Anduril and Qualcomm will have created more than an American-made computer. They will have helped restore the suppliers, production knowledge and technical workforce required to build the next one.

      For a company accustomed to tackling difficult national-security problems, the laptop may be one of Anduril’s most practical ideas yet.

      Sometimes rebuilding an industry begins with reopening the machine.

      More from this week’s LA startup and venture scene below.

      🤝 Venture Deals

        LA Companies

        • StimCardio raised an oversubscribed $30M Series A led by Metis MedTech, with participation from Catalyst Health Ventures and other investors. The Los Angeles medical device company will use the funding to advance a pivotal study of Rhyvive, its investigational wrist-worn therapy designed to reduce recurring atrial fibrillation after catheter ablation, and prepare for an FDA submission. - learn more
        • Gardena-based Neuron Industries raised an oversubscribed $10M seed round co-led by FCVC and Obvious Ventures, with participation from Y Combinator, Thin Line Capital, Zee Prime Capital and Founder Factor. The company will use the funding to develop and launch its AI-powered industrial control platform, expand its product line and establish domestic production as it works to help engineers automate new factories and machinery more quickly. - learn more
        • Offe Market raised a $3M seed round led by Slauson & Co., bringing the off-price retail marketplace’s total funding to $4.3M. The company will use the capital to expand its commerce platform with AI-powered pricing and inventory tools, personalized recommendations and live shopping features designed to help brands sell excess merchandise without sacrificing control over presentation or pricing. - learn more
        • Loamy raised a $6M seed round led by Zeal Capital Partners, with participation from LA investors Slauson & Co., Supply Change Capital and Amplify.LA, bringing its total funding to $10M. The company will use the capital to expand its engineering and sales teams, advance its AI platform and enter additional food categories as it helps growers, packers and distributors reduce waste and prevent rejected shipments. - learn more

        LA Venture Funds
        • MaC Venture Capital co-led Rendezvous Robotics’ oversubscribed $20M seed round alongside Toyota Ventures, marking the space startup’s first priced financing. The company will use the funding to develop its next-generation modular spacecraft, expand its team and prepare for flight demonstrations of technology that allows spacecraft components to assemble and reconfigure autonomously in orbit. - learn more
        • BOLD Capital Partners participated in General Compute’s $100M Series A, which was co-led by Blackbird and Abstract. The company will use the funding to scale its AI inference cloud, which deploys specialized chips from companies including Cerebras, SambaNova and Positron AI to help customers run AI workloads faster without managing the underlying infrastructure. - learn more
        • Mantis Venture Capital participated in Vera Health’s $28.5M Series A, which was led by Threshold Ventures and brought the clinical AI company’s total funding to $32M. Vera will use the capital to strengthen its medical-evidence infrastructure, enter new healthcare markets and expand partnerships with medical societies, publishers and health systems. - learn more

        LA Exits

        • Breastfeeding platform Swehl was acquired by Willow Innovations alongside infant-feeding technology company Momtech, with financial terms undisclosed. Swehl’s educational resources and community programs will anchor Willow World, a new platform designed to expand Willow’s business beyond wearable breast pumps and support mothers across more of the postpartum journey. - learn more
        • SmartLess Mobile was acquired by Noble Mobile and will transition to the Noble brand as the companies combine their efforts to offer simpler, more affordable wireless service. Existing customers will retain their plans, prices, phone numbers and T-Mobile 5G coverage, while gaining the ability to use their data in Mexico and Canada at no additional cost; financial terms were not disclosed. - learn more

          Download the dot.LA App

          Your Bank Wants to Cancel Your Subscriptions

          🔦 Spotlight

          Hello, LA.

          Somewhere between the streaming service you still use and the free trial you forgot to cancel, recurring payments have become a surprisingly complicated part of modern financial life.

          Los Angeles-based ScribeUp believes your bank should help manage them.

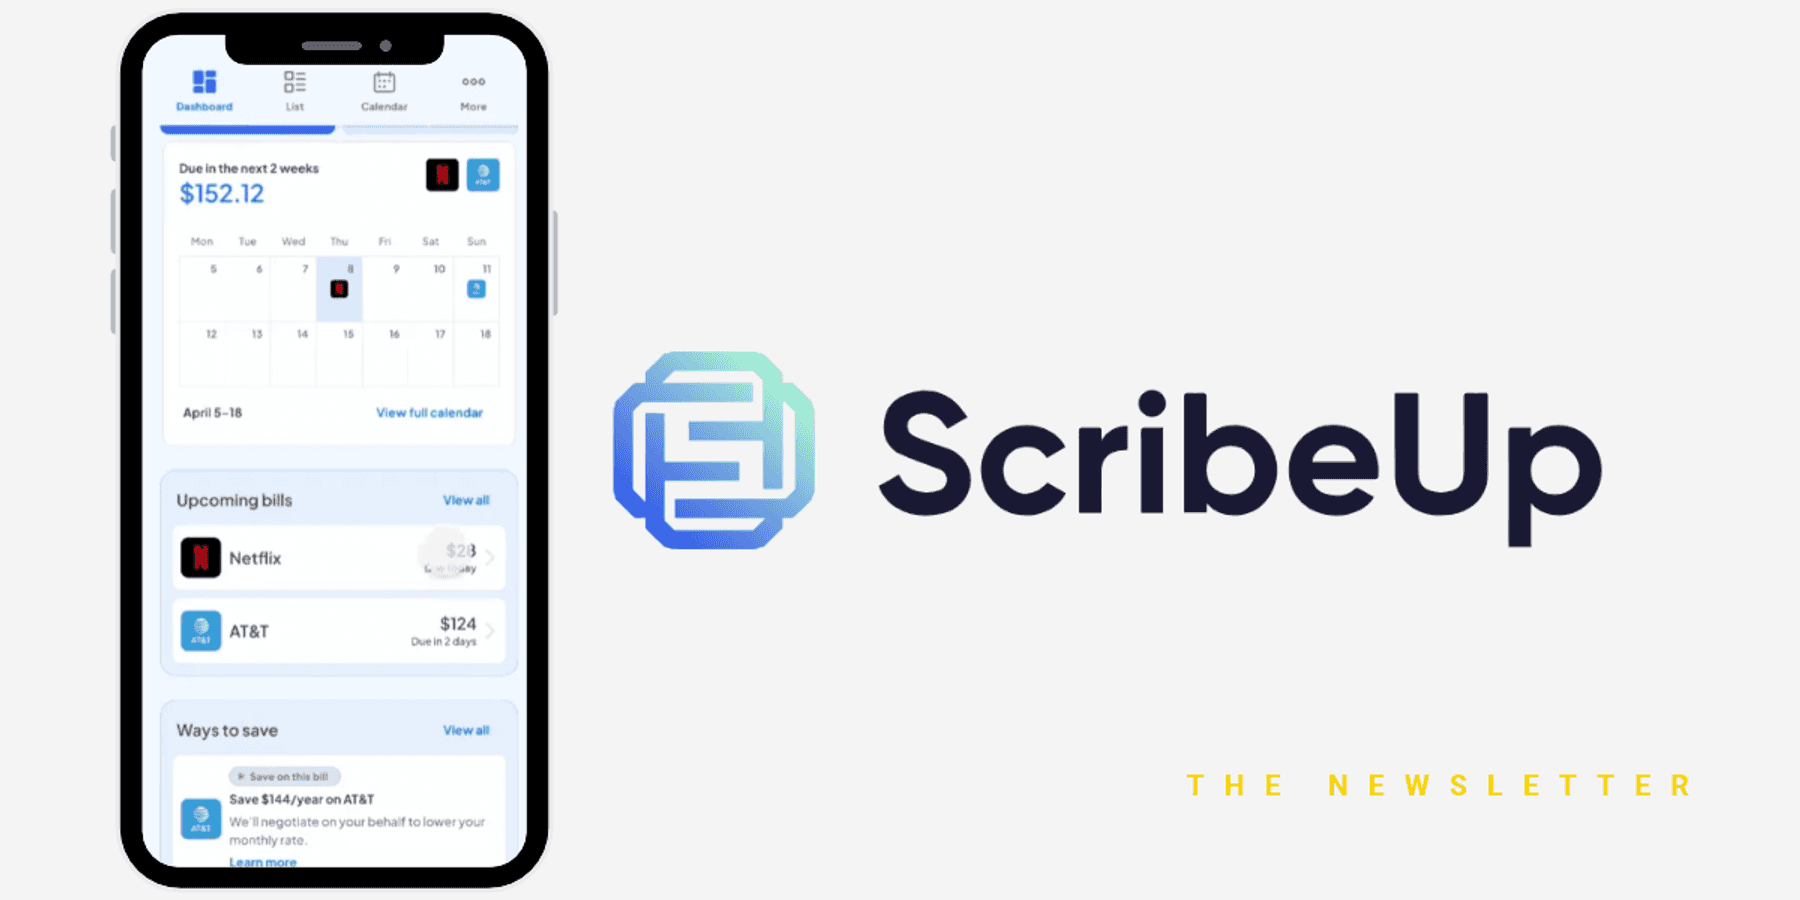
          The fintech company raised a $13M Series A led by Curql, with participation from Mucker Capital and Service Ventures. The financing includes $10M in equity and a $3M venture debt facility, bringing ScribeUp new capital to expand its team, accelerate sales and further develop its AI-powered bill-management technology.

          The product is designed to live directly within the apps of banks, credit unions, fintechs and neobanks. Instead of simply showing customers that a recurring charge occurred, ScribeUp gives them tools to do something about it.

          That could mean canceling a forgotten subscription, changing a payment method, accessing an advance or exploring refinancing options for an outside loan, all without leaving the financial institution’s app.

          It sounds like a useful feature. It is also part of a much larger contest over who gets to manage the consumer’s financial life.

          For years, banks have held customers’ money while third-party apps have increasingly helped them understand and manage it. Budgeting platforms organize spending. Subscription services identify recurring charges. Fintech apps recommend ways to save, borrow or invest.

          Now AI assistants are beginning to combine those functions into a single interface capable of not only analyzing financial information, but acting on it.

          That creates a risk for traditional financial institutions. If consumers begin turning to an outside app whenever they need to cancel a service, manage a bill or make a financial decision, their bank could become little more than the infrastructure beneath someone else’s customer experience.

          ScribeUp offers banks a way to compete without building that technology themselves.

          Its platform combines recurring-payment information with the financial context a bank already has, including balances, cash flow and payment timing. That allows a financial institution to do more than flag an upcoming charge. It can potentially recommend and execute an action based on the customer’s broader financial position.

          ScribeUp says its technology is already used by more than 60 banks, credit unions, fintechs and neobanks. It can be added through an API, software development kit or embedded interface, allowing institutions to introduce bill-management features without creating the underlying infrastructure from scratch.

          The new funding will support more advanced AI capabilities that can take action across different billers. That distinction matters. The first generation of personal finance software helped people see where their money was going. The next generation wants permission to do something about it.

          For banks, the opportunity is straightforward: become more useful before another app takes their place.

          For consumers, the appeal may be even simpler. Most people do not want another financial dashboard. They want the unwanted charge to stop.

          The next battle in banking may not be over who holds your money.

          It may be over who gets to press cancel.

          More from this week’s LA startup and venture scene below.

          🤝 Venture Deals

            LA Companies

            • International Dance League raised a $15M Series A led by Elysian Park Ventures, with participation from Sony, KB Partners, APEX, Yamaha Music Innovations Fund and October Ventures. Following a debut season that sold out all six events and generated 2B views, IDL will use the funding to expand its tour, strengthen team and dancer operations, improve broadcast production and develop new fan experiences for 2027. - learn more
            • Santa Fe Springs-based DrizzleX raised a $6.8M Series A-2 led by Israel Investment Fund Group, with several of the water-management platform’s own customers also investing. The company will use the funding to expand sales, streamline hardware manufacturing, build partnerships and develop new products that help property owners detect leaks, reduce water use and lower operating costs. - learn more
            • POV Beauty raised an undisclosed Series A led by Silas Capital, with participation from RÉDO Capital and existing investor Imaginary Ventures. The skin-prep brand will use the funding to build on its nationwide Sephora launch, expand its team and TikTok Shop presence, and develop more skincare-makeup hybrid products. - learn more

            LA Venture Funds
            • Chapter One participated in Warp Sciences’ $215M Series A, which was led by Lightspeed and included a large group of venture firms and angel investors. The company is building AI-powered, increasingly automated laboratories that will manufacture and test molecules for drug developers, aiming to accelerate preclinical research while expanding scientific infrastructure in the U.S. - learn more
            • Capital Group participated in Legora’s $550M Series E, which was led by Atreides Management and valued the legal AI company at $8.8B. Legora will use the funding to expand across the U.S. and international markets while developing new capabilities for its agentic operating system, which is used by more than 140,000 legal professionals. - learn more
            • Group 11 participated in CapitalOS’ $21.9M Series A, which was led by LGVP and included WEX Venture Capital, Great North Ventures and Night Capital. CapitalOS will use the funding to scale its infrastructure, which enables B2B software platforms to quickly offer financial products while outsourcing functions such as compliance, risk management and underwriting. - learn more
            • Starshot Capital participated in IMIO’s $12M funding round, which was led by Sofinnova Partners and included Chipotle’s Cultivate Next, Grow Together Salinas, Earth Foundry and Serra Ventures. The agricultural biotechnology company will use the capital to build a Chicago headquarters, laboratory and manufacturing facility for its freeze-dried microbial products, which are designed to improve soil health and crop yields. - learn more
            • SUM Ventures participated in Vectorial’s $3M seed round, which was co-led by Smilegate and SenseAI Ventures and included several investors connected to UC Berkeley and Stanford. The startup will use the funding to scale its AI-powered consumer research platform, which lets companies test products, marketing campaigns and AI agents against simulated audiences before launching them publicly. - learn more
            • Wave Function Ventures participated in Stellios Technologies’ oversubscribed $5M pre-seed round alongside Sofreh Capital, Cubit Capital, Mana Ventures, Atoms & Bits and other investors. The Austin-based company will use the funding to deliver its first high-power microwave systems, establish domestic research and manufacturing facilities, grow its team and advance technologies spanning directed energy, compact fusion and next-generation propulsion. - learn more
            • Upfront Ventures participated in Daytona’s $60M Series B, marking the Santa Monica firm’s third investment round with the company. Led by FirstMark Growth, the financing valued Daytona at $1B and will help the startup expand sales and engineering for its cloud infrastructure, which provides secure virtual computers where AI agents can execute tasks. - learn more
            • Core Innovation Capital participated in Delegance Brokerage’s $3.1M pre-seed round, which was led by Grit Capital Partners and included Gilgamesh Ventures and Outside VC. The AI-powered commercial insurance brokerage will use the funding to hire licensed brokers and engineers and expand partnerships as it promotes a flat 5% fee model in place of traditional commissions. - learn more
            • Core Innovation Capital participated in Prism Data’s $20M Series A, which was led by Story Ventures and included FINTOP Capital, Obvious Ventures, 1st & Main Growth Partners and Mana Ventures. Prism will use the funding to expand its cash-flow underwriting technology, AI infrastructure and data science team while growing across the U.S. and Canada and preparing for international expansion. - learn more

            LA Exits

            • Sanctuary has been acquired by WSG Brands, adding the contemporary women’s label to a portfolio that includes Von Dutch, Nasty Gal and Allbirds. The purchase price was not officially disclosed, though earlier documents placed it at $67M; WSG plans to expand Sanctuary internationally and into new categories, while founders Ken and Debra Polanco will remain involved. - learn more
            • SecureNet Solutions was acquired by CompassMSP, expanding the managed IT and cybersecurity provider’s presence on the West Coast. The deal gives SecureNet’s real estate, healthcare and professional services clients access to CompassMSP’s national cybersecurity, compliance and advisory resources while retaining their existing service team; financial terms were not disclosed. - learn more

              Download the dot.LA App

              RELATEDEDITOR'S PICKS
              Trending